




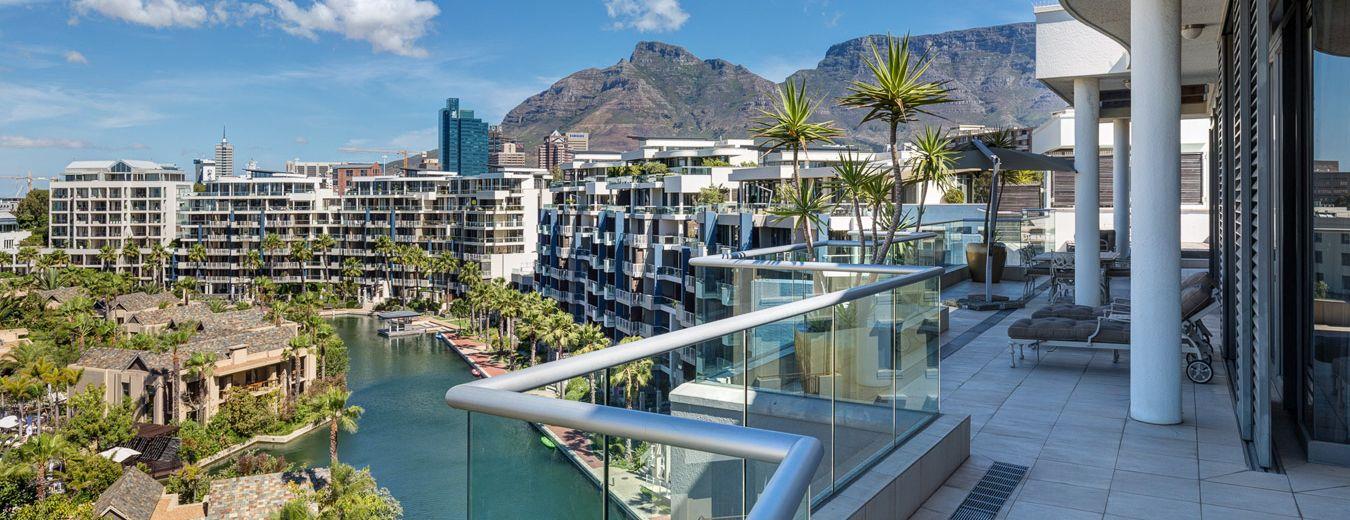
“South Africa’s residential property market recorded 7.6% annual growth in September 2026, with Cape Town leading at 11%, outperforming inflation at 4.0%. While metros like Durban and Mangaung lag, they provide affordability and leverage for buyers, underscoring regional disparities in the housing market.”
South Africa’s real estate development sector has entered September 2026 with renewed vigor, defying inflationary pressures and global economic uncertainty. The latest data reveals that national property prices rose 7.6% year-on-year, compared to consumer inflation at 4.0%. This remarkable performance underscores the resilience of the housing sector, even amid elevated interest rates and cautious household borrowing.
National Trends
- First-time buyers now account for 54.5% of home loan applications, reflecting affordability improvements and government subsidies like the Finance Linked Individual Subsidy Program (FLISP).
- The prime lending rate remains at 10.50% and the repo rate at 7.00%, stabilizing borrowing conditions.
- Pre-owned properties rose 8.5% nationally, outperforming new builds at 1.3%.
- Freehold properties grew 8.8%, compared to sectional title units at 6.0%.
Metropolitan Performance
| Metro | Growth Rate | Key Drivers |
|---|---|---|
| Cape Town | 11% | Luxury demand, investor confidence |
| Nelson Mandela Bay | 6.4% | Solid regional demand |
| Johannesburg | 5.4% | Middle-income buyers |
| Buffalo City | 5.0% | Suburban expansion |
| Ekurhuleni | 4.9% | Infrastructure projects |
| Durban | 3.7% | High stock availability |
| Pretoria | 3.8% | Entry-level opportunities |
| Mangaung | 2.8% | Below inflation, buyer leverage |
Economic Context
- Inflation cooled slightly, with CPI at 5.5% in August 2026.
- Household debt-to-income ratio stands at 61.8%, reflecting cautious but sustainable borrowing.
- Elevated interest rates remain a challenge for affordability, but government subsidies and transfer duty exemptions up to R1.2 million continue to support entry-level buyers.
Buyer Opportunities
- Slower-growth metros like Mangaung and Durban provide greater negotiating power and more stock availability.
- Cape Town remains premium, but affordability challenges persist for first-time buyers.
- Entry-level buyers benefit from subsidies and exemptions, making land and property ownership more accessible.
Risks and Challenges
- Elevated interest rates remain a challenge for affordability.
- Regional disparities highlight the importance of local employment and infrastructure conditions.
- Inflationary pressures, though easing, remain a risk to household budgets.
Conclusion
The South African residential property market in September 2026 demonstrates resilience, outperforming inflation and offering diverse opportunities across metros. Cape Town continues to lead the charge, while slower-growth regions provide affordability and leverage for buyers. This dynamic landscape underscores the importance of regional economic conditions, government support, and investor confidence in shaping the future of real estate development in South Africa.



