




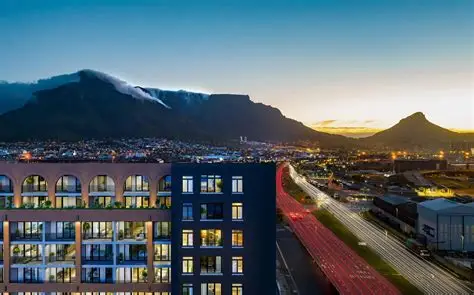
“South Africa’s residential property market in September 2026 is defined by strong momentum from first-time buyers, who now account for more than half of all home loan applications. While Cape Town leads growth at 11%, affordability ceilings and regional disparities highlight a market split between resilient entry-level demand and slower-performing metros.”
The South African residential property market in September 2026 presents a fascinating paradox: while national house price growth is slowing in real terms due to affordability ceilings, certain regions and buyer segments are thriving. First-time buyers, supported by aggressive bank lending and government subsidies, are reshaping the dynamics of the housing sector. Cape Town continues to dominate growth, while metros such as Durban and Mangaung highlight affordability opportunities for buyers willing to compromise on pace of appreciation.
National Trends
- House price inflation: 3.4% (Lightstone Residential Property Index, September 2026)
- Prime lending rate: 10.50% (SARB MPC, September 2026)
- Repo rate: 7.00% (SARB MPC, September 2026)
- First-time buyer share: 51.6%–54.5% of home loans (ooba Oobarometer, Q3 2026)
- Average purchase price for first-time buyers: R1.3–R1.4 million
This data reveals a market of two halves: properties below R1.5 million remain resilient, while higher-end segments face affordability challenges.
Regional Performance
| Metro | Growth Rate (YoY) | Key Drivers |
|---|---|---|
| Cape Town | 11% | Luxury demand, investor confidence |
| Johannesburg | 5.4% | Middle-income buyers |
| Durban | 3.7% | High stock availability |
| Mangaung | 2.8% | Affordability, buyer leverage |
Drivers of Demand
- First-time buyers: Over half of all loans, supported by reduced deposit requirements and 100%+ loans.
- Government subsidies: Programs like FLISP and transfer duty exemptions up to R1.2 million boost affordability.
- Infrastructure reliability: Well-run municipalities and off-grid features (solar, boreholes) command premiums.
Risks and Challenges
- Elevated interest rates (prime at 10.50%) continue to strain affordability.
- Household debt-to-income ratios remain high at 61.8%–62.8%, signaling stretched budgets.
- Regional disparities highlight the importance of local employment and municipal competence.
Outlook
The outlook for South Africa’s residential property market in late 2026 is cautiously optimistic. While affordability ceilings limit upper-end growth, entry-level and mid-market segments are buoyed by first-time buyers and government support. Cape Town will likely remain the premium growth hub, but slower metros provide opportunities for affordability-focused buyers.



