


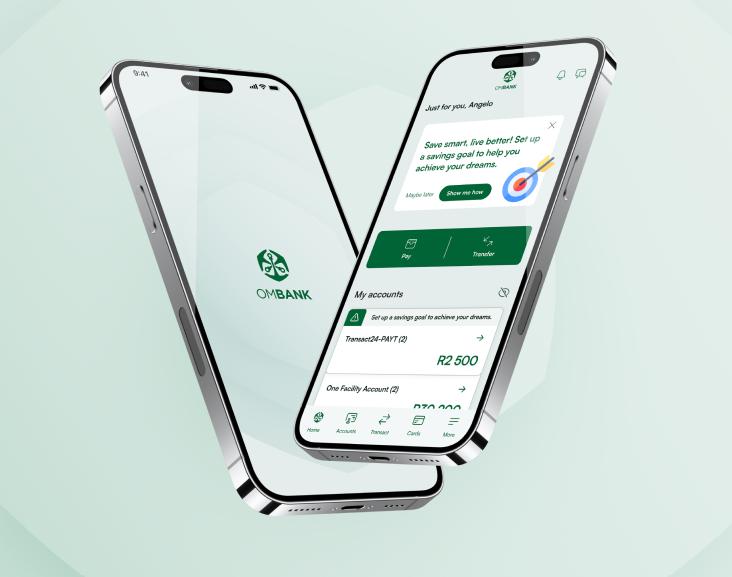
“Old Mutual’s OM Bank is accelerating its push into South Africa’s competitive banking market after reaching about 1 million customers, with the lender targeting consumers earning between R15,000 and R50,000 a month. The bank plans to expand its customer base, deposits and lending operations while using Old Mutual’s existing financial-services ecosystem to compete with established banks and other newer entrants.”
OM Bank Steps Up Competition in South Africa’s Banking Industry
South Africa’s banking sector is entering another phase of competition as Old Mutual’s OM Bank seeks to establish itself as a significant player in a market dominated by long-established financial institutions. The latest development, reported on 25 September 2026, highlights the scale of Old Mutual’s ambition as its banking operation approaches a major customer milestone and prepares for further expansion into deposits, lending and other financial services.
OM Bank is part of Old Mutual, one of Africa’s major insurance and financial-services groups. According to Moneyweb’s report, the bank was created partly in response to the growing overlap between banking and insurance. Old Mutual CEO of OM Bank Clarence Nethengwe said the company viewed the increasing movement of traditional banks into insurance as an important factor behind its decision to establish a banking operation.
The development illustrates how South Africa’s financial-services industry is increasingly organised around broader ecosystems rather than individual products. Banks are moving into insurance and investment services, while insurers and other financial-services companies are entering banking. At the same time, digital-first banks and fintech businesses are attempting to attract customers with technology-driven services, competitive pricing and simplified financial products.
OM Bank’s Rapid Customer Growth
One of the most significant aspects of the latest OM Bank development is the speed at which the lender has attracted customers.
Moneyweb reported that OM Bank had reached approximately 1 million customers by September 2026. The bank reportedly attracted nearly 4,500 customers per day during the eight months to August, demonstrating the potential scale of Old Mutual’s existing customer relationships and distribution capabilities.
The customer base is also notable because OM Bank is not relying exclusively on existing Old Mutual clients. According to the report, approximately 68% of its customers were already Old Mutual customers, while 32% were new to the broader Old Mutual group.
That distinction matters because a banking operation attached to an established financial-services group can potentially use existing relationships to reduce the cost and time required to acquire customers.
However, customer numbers alone do not determine whether a bank becomes financially successful. Banks need customers who actively transact, maintain deposits, use credit and purchase other financial products. Consequently, OM Bank’s next stage will involve converting its rapidly expanding customer base into a sustainable source of revenue.
A Crowded Banking Market
OM Bank is entering a highly competitive South African banking environment.
Moneyweb reported that around 81% of South Africans already hold a bank account, meaning that the market is not primarily about bringing completely unbanked consumers into formal banking. Instead, new banks must persuade existing customers to open additional accounts, switch their primary banking relationships or use multiple financial providers.
The traditional large banks continue to control a substantial portion of South Africa’s banking assets. Moneyweb reported that Standard Bank Group, FirstRand, Absa Group and Nedbank Group collectively account for approximately 83% of the country’s R5.8 trillion in banking assets.
This concentration creates a significant barrier for new entrants. Established banks already possess large customer bases, extensive technological infrastructure, recognised brands and long-standing relationships with individuals and businesses.
Nevertheless, the market has changed considerably with the growth of digital banking. Consumers can increasingly open accounts remotely, make payments through mobile applications and compare financial products without visiting traditional branches.
That shift has created opportunities for newer banks, including OM Bank, to compete through technology and integrated financial products.
Old Mutual’s Financial Commitment
Building a bank requires substantial investment, particularly during the early years when infrastructure, technology, compliance systems and customer acquisition costs can exceed revenue.
According to Moneyweb, Old Mutual spent approximately R2 billion establishing OM Bank and injected another R3.2 billion between 2025 and 2026. The group has budgeted a further R2 billion by 2028, when the bank is expected to reach break-even or potentially profitability.
The investment reflects the long-term nature of Old Mutual’s banking strategy.
Old Mutual previously operated financial products that provided customers with transactional and lending services. The creation of a dedicated bank gives the group an opportunity to bring more of those services into a single banking ecosystem.
Earlier reporting by Business Times showed that OM Bank had already accumulated hundreds of thousands of customers during its initial expansion. The bank was targeting between 2.5 million and 2.8 million customers by 2028, alongside a deposit target of up to R10 billion.
The latest report puts the customer ambition at as many as 2.8 million by 2028.
Focus on Middle-Income Customers
OM Bank is focusing particularly on consumers earning between R15,000 and R50,000 per month.
This segment is strategically important because customers in this income range may use several financial products, including transactional accounts, savings, insurance, personal loans, investments and potentially home-finance products.
The approach also places OM Bank in competition with banks that already have substantial experience serving South Africa’s middle-income and mass-affluent customers.
Rather than competing solely for basic transaction accounts, OM Bank is therefore positioning its banking operation within a wider financial-services relationship.
This strategy is consistent with Old Mutual’s broader business model. The company already has insurance, savings, investment and lending capabilities. Combining these services with banking could allow the group to offer customers a wider range of products through a single financial relationship.
Deposits Become an Important Target
Another major component of OM Bank’s expansion strategy is deposits.
Moneyweb reported that Old Mutual plans to use an existing insurance-savings product to help increase deposits in the banking operation. That product has accumulated as much as R32 billion over time and reportedly grows by approximately R1.5 billion annually. OM Bank wants to use this ecosystem to help build deposits to as much as R10 billion by 2028.
Deposits are central to banking because they provide an important source of funding for lending activities.
For OM Bank, increasing deposits could therefore support the next stage of its development as it moves beyond customer acquisition and toward broader banking operations.
The challenge will be to encourage customers to keep meaningful balances with the bank while offering competitive savings products and maintaining appropriate liquidity and risk controls.
Lending Could Become the Next Growth Engine
OM Bank’s strategy also extends beyond transaction accounts and deposits.
Earlier reporting indicated that the bank intends to expand into lending, including unsecured and secured lending, subject to the relevant regulatory processes. Business Times reported that Old Mutual Finance had an existing unsecured lending book of around R16 billion and approximately 300,000 customers, with plans to increase that lending book to between R23 billion and R26 billion over three years.
The integration of existing lending operations with the bank could therefore provide OM Bank with an established foundation for expanding its credit business.
However, lending also introduces additional risks. Banks must carefully assess borrowers’ ability to repay loans, particularly when households face pressure from interest rates, fuel costs and other living expenses.
That issue is particularly relevant following the South African Reserve Bank’s September 2026 monetary-policy decision.
Interest Rates Add Another Layer of Complexity
On 23 September, the South African Reserve Bank increased the policy rate by 25 basis points to 7.25%, effective from 25 September. The central bank said the decision was unanimous and linked the higher inflation outlook largely to rising fuel prices and wider global supply shocks.
The Reserve Bank reported that headline inflation was 4.4% and warned that inflation could remain elevated into 2027, largely because of fuel and services inflation. It projected that inflation would return to the 3% target toward the end of 2027.
For banks, changes in interest rates affect both lending and savings.
Higher interest rates can increase borrowing costs for households and businesses. At the same time, they can potentially improve returns for savers and affect the pricing of deposits.
For OM Bank, therefore, expansion into lending will take place against a monetary environment where affordability and credit risk remain important considerations.
Competition Extends Beyond Traditional Banks
OM Bank is not competing only with the established banking groups.
South Africa has also seen the expansion of digital and technology-oriented financial institutions. The Prudential Authority’s 2026 list of locally controlled banks includes OM Bank alongside institutions such as Nedbank, Standard Bank, Sasfin and GoTyme Bank.
The competitive environment means customers have more options than they did when South Africa’s banking industry was dominated primarily by a small group of large institutions.
Insurance companies are also becoming increasingly involved in banking. Moneyweb reported that Sanlam has received approval to provide transactional banking services in partnership with GoTyme Bank, while Discovery has already operated a banking business.
This convergence between banking and insurance is one of the central developments shaping the industry.
What OM Bank’s Expansion Means for Customers
For South African consumers, increased competition could lead to changes in the products and services offered by financial institutions.
Banks may compete through transaction fees, savings rates, lending products, digital experiences, loyalty programmes and integrated financial services.
However, consumers will still need to compare individual products carefully because lower fees in one area do not necessarily mean lower overall banking costs.
The growth of digital banking also places greater importance on cybersecurity, data protection and fraud prevention. The Banking Association South Africa has warned consumers about fraudulent applications and QR-code phishing, reflecting the broader security challenges associated with increasingly digital financial services.
As more financial activity moves onto mobile and digital platforms, banks must therefore balance convenience with strong security and regulatory controls.
The Road Ahead for OM Bank
OM Bank’s latest customer figures demonstrate that Old Mutual has been able to attract customers at considerable speed. The more difficult phase may now be converting that scale into a sustainable banking business.
The bank has set ambitious targets for customer growth, deposits and profitability. It also has access to Old Mutual’s existing insurance, savings and lending ecosystem, which could provide opportunities that are not easily available to a completely new financial institution.
At the same time, OM Bank faces established competitors with significant assets and customer relationships. The banking market is already highly penetrated, meaning that growth will largely depend on winning customers from existing providers or increasing the range of financial products used by existing customers.
The September interest-rate increase adds another consideration, particularly for lending and household affordability. Meanwhile, global economic uncertainty, higher fuel costs and inflation pressures remain relevant to the wider banking environment.
For now, OM Bank’s expansion represents another significant development in the restructuring of South Africa’s financial-services landscape. Its progress will be closely tied to whether it can transform rapid customer acquisition into deeper customer relationships, growing deposits, responsible lending and sustainable profitability.
The latest report therefore points to a broader trend rather than simply the arrival of another bank: South Africa’s financial industry is increasingly becoming a contest between integrated financial ecosystems, digital platforms, insurers and traditional banks. OM Bank’s next phase will show how effectively Old Mutual can use its established financial-services base to compete within that changing market.