


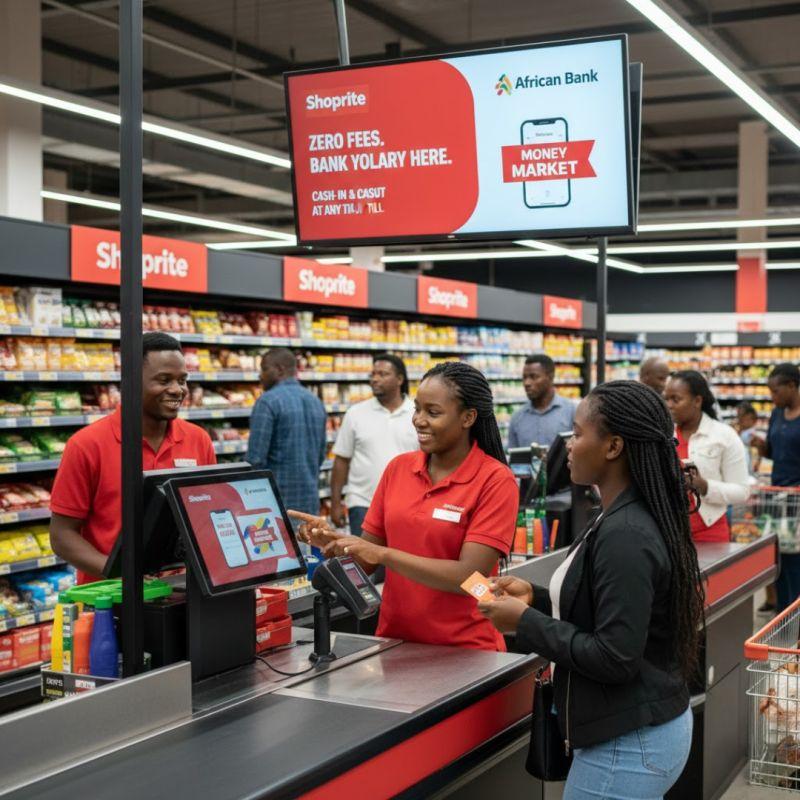
“Shoprite Group has entered into an agreement in principle with Investec Bank to expand its financial services business, including a planned debit card and an enhanced transactional account, subject to regulatory approval. The partnership could strengthen financial inclusion and intensify competition in South Africa’s banking sector by combining Shoprite’s extensive retail network and customer base with Investec’s banking infrastructure, regulatory capabilities and financial expertise.”
Shoprite and Investec Banking Partnership Signals Major Shift in South Africa’s Financial Services Industry
Shoprite Expands Banking Ambitions Through Investec Partnership
South Africa’s financial services industry is preparing for another significant competitive development following an agreement in principle between Shoprite Group and Investec Bank to expand the retailer’s transactional banking offering. Announced on 9 November 2026, the partnership represents a strategic move that could reshape how millions of consumers access everyday banking services.
The agreement will see Investec become the banking sponsor for an expanded Shoprite Financial Services transactional account, including the proposed introduction of a debit card. Although the arrangement remains subject to regulatory approval, it highlights the growing importance of retail-based financial services in South Africa’s evolving banking environment.
The development is particularly significant because Shoprite already operates one of the country’s largest retail networks and has developed an established financial services customer base through its Money Market account. Combining this reach with Investec’s banking infrastructure could create new opportunities for customer acquisition, payments and retail deposits.
Investec Provides Banking Infrastructure and Regulatory Expertise
Under the proposed alliance banking arrangement, Shoprite Financial Services will continue managing the customer-facing banking proposition through the group’s brands, stores and digital channels.
Investec, meanwhile, will provide the underlying banking infrastructure, banking licence, regulatory framework and balance sheet support necessary to operate the expanded transactional offering.
This structure allows Shoprite to extend its banking services without establishing an independent bank. Consequently, the retailer can concentrate on customer engagement, distribution and product development while relying on Investec’s established financial services capabilities.
For Investec, the partnership creates an opportunity to reach customer segments beyond its traditional private banking and corporate banking markets.
Investec Group chief executive Fani Titi said the agreement would enable the bank to access new markets and expand its capabilities while maintaining its existing strategic focus.
The bank also expects the partnership to deepen its involvement in South Africa’s payments ecosystem and broaden its access to retail deposits.
Importantly, the agreement is non-exclusive. Shoprite has confirmed that it will not replace existing relationships with other banks, payment providers, financial services companies or loyalty partners.
Shoprite’s Existing Financial Services Business Creates a Strong Foundation
Shoprite’s banking ambitions build on an established financial services platform.
The retailer already operates a Money Market account that has attracted millions of customers, including individuals who previously experienced limited access to conventional banking services.
According to reporting by TechCentral, Shoprite’s Money Market account had approximately 4.3 million customers, demonstrating the scale of its existing financial services operation.
The account allows customers to undertake several everyday financial activities, including depositing money, receiving qualifying payments, making withdrawals and managing basic transactions.
The retailer has progressively expanded its financial services offering through additional products and partnerships.
Its financial services activities include money transfers, cash deposits and withdrawals, bill payments, prepaid electricity purchases, airtime purchases and selected insurance and credit offerings.
The proposed debit card would represent another important development because it could make the account more useful for everyday purchases and payments outside the retailer’s own stores.
For customers, this could mean greater convenience and more flexibility when accessing their money.
For Shoprite, it creates opportunities to strengthen customer relationships, increase engagement with its digital platforms and develop additional financial services revenue streams.
Debit Card Introduction Could Increase Customer Convenience
One of the most important features of the proposed partnership is the introduction of a debit card.
A debit card could allow customers to access funds in their transactional accounts through a broader range of payment channels, potentially including retailers and other merchants accepting card payments.
The companies have indicated that the expanded offering is expected to provide greater payment flexibility, improved security and access to additional digital and everyday payment solutions.
However, important details remain outstanding.
Neither company has announced a confirmed launch date, final account pricing or the complete list of debit card features.
The companies have also not provided comprehensive details regarding eligibility requirements, transaction limits or whether the expanded account will support debit orders.
These details will be important in determining how competitive the new account becomes relative to established banking products.
Consumers are likely to compare monthly fees, cash withdrawal costs, payment functionality, digital accessibility and customer support when deciding whether to adopt the expanded offering.
The eventual commercial success of the partnership will therefore depend not only on distribution but also on the affordability and usefulness of the account.
Retail Banking Competition Continues to Intensify
The Shoprite-Investec partnership arrives as South Africa’s financial services market experiences increasing competition from retailers, fintech businesses and established financial institutions.
Traditional banking institutions have historically maintained substantial control over transactional banking, payments and deposit-taking services.
However, retailers increasingly recognise that financial services can complement their existing businesses by improving customer loyalty and creating additional sources of income.
Shoprite’s nationwide footprint provides a substantial competitive advantage.
The group operates thousands of stores across South Africa and other African markets, creating extensive physical access points for customers who may find conventional bank branches inconvenient.
Its grocery operations also generate frequent customer interactions, allowing the company to introduce financial services through an existing commercial relationship.
Other retailers are pursuing similar strategies.
Pepkor has been developing its banking ambitions following regulatory approval to establish a bank, while Pick n Pay has offered banking-related services through its partnership with TymeBank.
These developments demonstrate that financial services are becoming an increasingly important component of retail competition.
Shoprite’s partnership with Investec could strengthen this trend by showing how a retailer can expand transactional banking without independently building a complete banking infrastructure.
Financial Inclusion Remains a Major Opportunity
Financial inclusion is one of the potential benefits associated with the partnership.
South Africa has an established banking industry, but access to affordable and convenient financial services remains important for lower-income consumers, informal traders and individuals living far from traditional banking facilities.
Shoprite’s stores provide an extensive physical distribution network that could help bridge some of these accessibility challenges.
Customers may be able to interact with financial services through familiar retail environments rather than relying exclusively on dedicated bank branches.
The combination of physical stores and digital platforms could also support consumers who prefer different methods of accessing financial services.
For informal traders and small businesses, convenient payment facilities and accessible transactional accounts may support everyday commercial activities.
Nevertheless, financial inclusion requires more than simply making an account available.
Affordable fees, transparent terms, accessible customer service, reliable technology and appropriate consumer protection are essential.
The partnership’s impact will ultimately depend on whether customers can use the expanded offering effectively and economically.
If implemented successfully, the arrangement could contribute to broader participation in formal financial services and provide consumers with additional choices.
Investec Could Benefit From Broader Retail Deposits
For Investec, the partnership represents an opportunity to diversify its customer reach and expand its participation in transactional banking.
The bank has traditionally focused on private banking, wealth management and corporate financial services.
Shoprite’s customer base offers a different distribution opportunity, potentially providing access to substantial retail deposits and greater participation in everyday payment transactions.
Retail deposits can be strategically valuable because they support funding diversification and broader financial services activity.
However, the economics of mass-market transactional banking differ considerably from private banking.
Customer acquisition costs, account servicing, fraud prevention, transaction processing and technology infrastructure require careful management.
Investec will therefore need to balance the partnership’s growth opportunities against operational and financial considerations.
The arrangement also allows the bank to expand its capabilities through an established retail platform rather than independently creating an entirely new mass-market distribution network.
This approach could support growth while preserving Investec’s established business model.
The partnership’s contribution to the bank’s long-term performance will depend on customer adoption, account activity, deposit balances and the commercial terms agreed between the parties.
Digital Banking and Payments Become Increasingly Important
South Africa’s banking industry is undergoing significant changes as digital payments become increasingly important for consumers and businesses.
Mobile applications, electronic transfers, debit cards and digital payment services have transformed how customers interact with financial institutions.
Shoprite’s proposed expanded transactional account fits within this broader transformation.
The retailer already has extensive digital capabilities through its shopping platforms and customer loyalty ecosystem.
Financial services integration could strengthen these platforms by allowing customers to undertake additional financial activities within familiar digital environments.
However, digital banking expansion also increases the importance of cybersecurity, fraud prevention and customer data protection.
Financial institutions must maintain robust authentication procedures, secure transaction processing and effective monitoring systems.
Customers also require clear information about how their personal information is collected, processed and protected.
As Shoprite and Investec develop their proposed offering, security and reliability will be critical to maintaining consumer confidence.
A convenient banking product must also demonstrate that customers’ money and information are protected appropriately.
Regulatory Approval Remains an Important Milestone
The partnership has not yet completed all the regulatory processes required for implementation.
The companies have explicitly stated that the agreement remains subject to regulatory approval.
This means customers should not interpret the announcement as confirmation that the expanded account or debit card is immediately available.
The regulatory process will be important in establishing the arrangements governing the banking infrastructure, customer protection and operation of the expanded services.
The companies have also not announced a final commercial launch timetable.
Further announcements are expected to clarify the product’s features, pricing, customer eligibility and operational arrangements.
Until those details become available, the partnership should be regarded as a proposed expansion rather than a fully launched banking product.
Outlook: A New Chapter for South African Retail Banking
The Shoprite-Investec partnership represents an important development in South Africa’s banking and financial services industry.
It combines the distribution advantages of a major retailer with the financial infrastructure of an established banking institution.
For Shoprite, the agreement supports its ambition to develop a broader financial services ecosystem and create additional value for customers beyond traditional grocery retailing.
For Investec, it offers an opportunity to expand its participation in transactional banking, reach new customer segments and strengthen its role in the payments market.
For consumers, the proposed debit card and expanded transactional account could provide additional banking options and potentially improve access to everyday financial services.
The partnership also illustrates a broader industry trend in which financial services increasingly extend beyond traditional bank branches and into retail environments, digital platforms and customer ecosystems.
Nevertheless, the ultimate impact will depend on regulatory approval, product pricing, security, customer adoption and the practical usefulness of the expanded account.
If successfully implemented, the arrangement could become an important example of how strategic partnerships are changing the delivery of banking services in South Africa.
South Africa’s banking competition is increasingly being shaped not only by traditional financial institutions but also by retailers capable of bringing banking closer to millions of everyday consumers.