


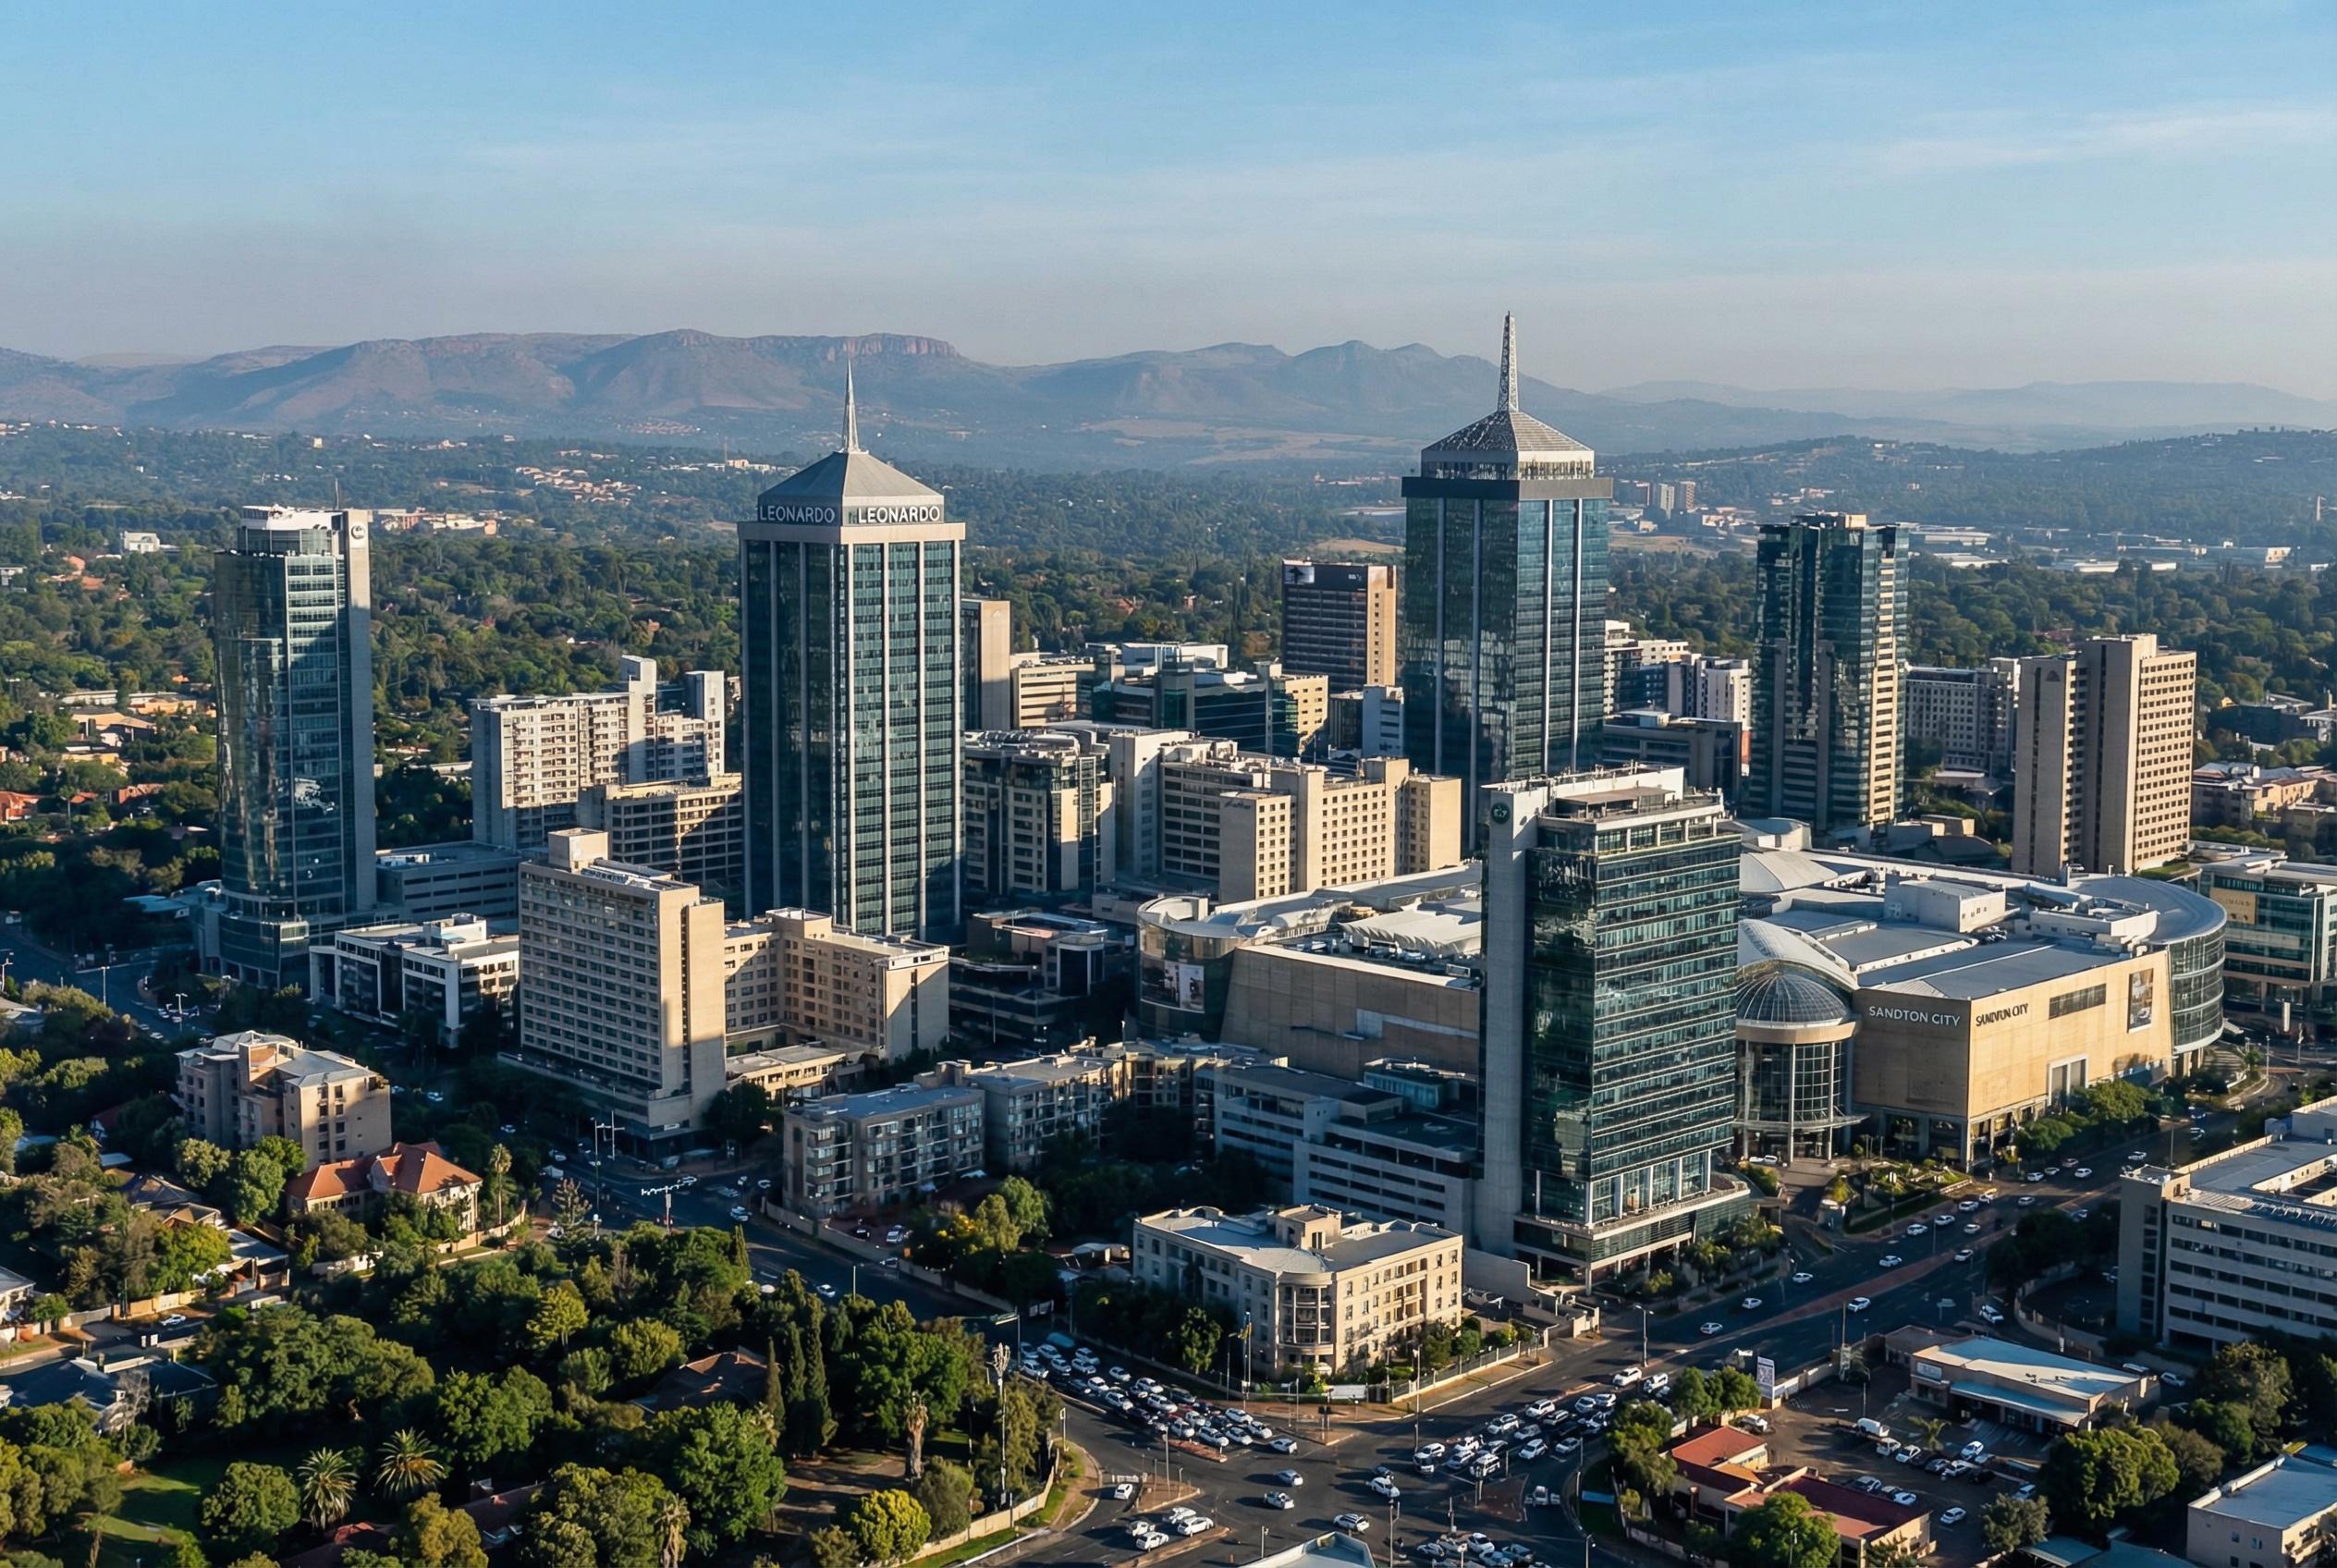
“South Africa’s national office vacancy rate reportedly fell to 11.8% in the third quarter of 2026, reflecting an improvement in office occupancy compared with the pandemic-era peak of 16.8% in mid-2022. However, prime office buildings are performing better than secondary properties, highlighting the importance of location, building quality, tenant demand and operating costs in the commercial property market.”
South Africa’s Office Vacancy Rate Falls to a Six-Year Low as Commercial Property Market Shows Signs of Recovery
South Africa’s commercial property sector is showing signs of gradual improvement, with the national office vacancy rate reportedly falling to 11.8% during the third quarter of 2026. The latest figures, attributed to the South African Property Owners Association (SAPOA) and reported by Tribedart on 10 October, indicate that the office market has moved further away from the disruption experienced during the COVID-19 pandemic. Nevertheless, the recovery remains uneven, with premium office buildings generally outperforming older properties and significant differences between major commercial centres.
Office Market Recovery Gains Momentum
The reported decline in office vacancies represents an important development for South African commercial real estate. According to the published report, the national vacancy rate reached 16.8% in mid-2022 before falling to 11.8% in the third quarter of 2026. This represents a reduction of five percentage points and suggests that demand for office accommodation has improved over the period.
Office vacancies matter because they influence rental income, building valuations, property investment decisions and the financial stability of landlords. When businesses occupy more office space, property owners can collect additional rental income, reduce vacancy-related expenses and potentially improve the performance of their investments.
However, a lower vacancy rate does not automatically mean every commercial building is profitable. Property owners must still consider rental incentives, operating costs, maintenance expenses, financing obligations and the quality of tenants occupying their buildings.
The latest figures therefore provide grounds for cautious optimism rather than a guarantee of a complete market recovery.
Premium Buildings Outperform Secondary Properties
One of the most important findings is the difference between higher-quality office buildings and older or less competitive properties. The report places national A-grade office vacancies at 9.5%, compared with 15.9% for B-grade offices.
This gap highlights how tenant expectations are influencing commercial property demand.
Modern businesses increasingly consider more than the amount of floor space available when choosing offices. Accessibility, parking, security, reliable infrastructure, energy efficiency, public transport connections and nearby amenities can all influence their decisions.
Premium properties may also offer modern meeting facilities, shared working areas, reliable connectivity and attractive environments that encourage employees to spend time in the office.
Conversely, older buildings may require significant investment to remain competitive. Outdated layouts, inefficient cooling systems, limited parking and high maintenance requirements can discourage prospective tenants.
For landlords, upgrading an existing property may be more attractive than accepting prolonged vacancies. Nevertheless, refurbishment costs must be compared with achievable rents, expected occupancy improvements and the length of prospective leases.
Investors should therefore examine individual buildings rather than relying exclusively on national vacancy figures when assessing opportunities.
Cape Town Leads Major Commercial Centres
Geographical differences also remain significant. The report identifies Cape Town as having the lowest office vacancy rate among the major centres discussed, at 6.9%. Tshwane recorded 8.9%, while Durban stood at 9.3%. Johannesburg had a higher reported vacancy rate of 14.7%.
These figures demonstrate that South Africa does not have a single, uniform commercial property market. Conditions vary according to local economic activity, infrastructure, tenant demand and the availability of suitable office accommodation.
Cape Town’s comparatively low vacancy rate indicates stronger occupancy conditions within the reported period. For property owners, this can support confidence in leasing prospects, although individual performance still depends on location, rental levels and building quality.
Tshwane and Durban also show comparatively lower vacancy rates than Johannesburg in the published figures. Businesses considering office locations may evaluate these cities according to workforce availability, customer access, operating expenses and proximity to government institutions, logistics networks or industrial facilities.
Johannesburg remains a major commercial centre, but its higher vacancy rate suggests that property owners must pay close attention to tenant requirements and the competitiveness of their buildings.
A building in a well-connected business district may perform differently from one in a location experiencing weaker demand, even within the same metropolitan area.
Changing Workplace Habits Reshape Demand
The shift towards hybrid working continues to influence the office market. Although employees have returned to offices in many businesses, working remotely for part of the week remains widespread, according to the published report.
This development changes how companies calculate their space requirements.
Previously, organisations often leased offices according to the number of employees they expected to accommodate simultaneously. Hybrid working can reduce the need for permanently assigned desks and encourage businesses to introduce shared workstations, collaboration areas and flexible meeting spaces.
Consequently, a company may renew its lease while occupying less floor space than before. Another business might relocate to a smaller but better-equipped office to improve its working environment without substantially increasing its property expenses.
These decisions create challenges for landlords whose buildings were designed around traditional office arrangements.
However, they also create opportunities. Owners who understand tenant needs can redesign available space, introduce flexible leasing arrangements and provide facilities that make offices more useful.
The objective is not simply to accommodate employees but to offer an environment that supports collaboration, productivity and business operations.
Commercial property owners who adapt to these changing requirements may be better positioned to attract and retain tenants.
Quality and Location Become Competitive Advantages
Property economist and University of Cape Town emeritus associate professor Francois Viruly, quoted in the report, describes the recovery as uneven and emphasises that occupiers may need different types of space. He also compares the future office environment with hospitality, where the quality of the experience is increasingly important.
This perspective highlights a broader transformation in commercial property management.
An office building is no longer competitive simply because it provides desks and enclosed rooms. Businesses may also consider the quality of shared facilities, the surrounding neighbourhood, convenient transport connections and opportunities for employees to interact.
For property owners, this means that investment decisions should begin with a clear understanding of the target market.
A building intended for financial services companies may require different security, technology and meeting facilities from a property designed for creative businesses or smaller professional firms.
Likewise, suburban offices may appeal to organisations seeking convenient parking and proximity to residential communities, while central business districts may attract companies that benefit from access to clients, transport and other businesses.
Location remains essential, but the meaning of a desirable location increasingly depends on the needs of the intended occupier.
Municipal Services and Operating Costs Remain Important
Even as occupancy improves, commercial property owners face the challenge of controlling operating expenses. Moneyweb’s property coverage has highlighted concerns about municipal charges and weak service delivery, issues that can place pressure on property investment.
Rates, electricity, water, security, cleaning, insurance and maintenance all affect the financial performance of office buildings.
When these expenses increase, landlords may attempt to recover some costs through lease agreements. However, tenants facing their own financial pressures may resist higher occupancy costs or seek more affordable premises.
Unreliable municipal services can create additional problems. Businesses may require backup power, water storage, alternative connectivity and enhanced security to maintain operations. These measures can increase capital expenditure and ongoing maintenance requirements.
Consequently, investors should evaluate the total cost of operating a property, not merely its purchase price or advertised rental rate.
Buildings with efficient energy systems, dependable infrastructure and effective maintenance programmes may offer advantages over properties requiring substantial corrective expenditure.
Nevertheless, improvements must be financially justified. Spending on upgrades does not guarantee higher rents or immediate occupancy gains, particularly in areas with considerable competing supply.
Implications for Investors and Property Owners
The latest vacancy figures offer useful information for investors assessing South Africa’s commercial real estate sector. Lower vacancies can support rental income and improve the outlook for properties capable of attracting reliable tenants.
However, investment decisions should account for differences between buildings, locations and tenant categories.
Investors should examine current occupancy, lease expiry dates, tenant creditworthiness, rental escalation provisions, outstanding maintenance requirements and the costs of attracting new occupants.
They should also consider whether asking rents reflect actual market conditions. A building advertised at an attractive rental rate may still produce disappointing returns if incentives are substantial or vacancies remain prolonged.
For listed property companies and real estate investment trusts, office performance is only one part of a broader portfolio. Retail, industrial, logistics, residential and hospitality assets can have different demand drivers and risk profiles.
The South African REIT Association provides additional industry information, including reporting on listed property performance and distribution growth.
Investors should combine this wider market context with individual company disclosures and professional financial advice before making investment decisions.
Opportunities for Refurbishment and Redevelopment
The performance gap between A-grade and B-grade offices raises an important question: what should owners do with buildings that struggle to attract tenants?
One option is refurbishment. Improvements to energy efficiency, building access, common areas, connectivity and internal layouts may make an existing property more appealing.
Another possibility is repositioning a building towards a different category of occupier. Smaller businesses, professional services firms and flexible workspace operators may have requirements that differ from those of large corporate tenants.
Where office demand is persistently weak, owners may also investigate alternative uses. Depending on zoning, planning permissions, building design and financial feasibility, some properties could potentially support mixed-use redevelopment or other commercial activities.
However, conversion is not always practical. Structural limitations, fire safety requirements, parking standards, municipal approvals and infrastructure capacity can create significant obstacles.
A careful feasibility assessment is therefore necessary before committing capital. Owners must establish whether the projected benefits justify the costs and risks involved.
Outlook for South Africa’s Commercial Property Market
South Africa’s office vacancy rate falling to 11.8% is an encouraging indicator, but the next stage of recovery will depend on whether stronger occupancy translates into sustainable rental income and improved property valuations.
Economic growth, business confidence, employment trends, borrowing costs and infrastructure reliability will influence companies’ decisions about expansion and office leasing.
At the same time, hybrid working and changing tenant expectations are likely to keep pressure on landlords to improve building quality and provide more flexible accommodation.
Cape Town’s reported vacancy rate of 6.9% and Johannesburg’s 14.7% demonstrate why national averages must be interpreted alongside local market conditions.
For prospective tenants, the market may offer opportunities to negotiate suitable space, particularly in buildings with vacancies or refurbishment requirements. For landlords, retaining existing tenants and maintaining competitive facilities may be as important as securing new leases.
The wider commercial property sector also depends on transparent municipal charges, effective infrastructure management and policies that encourage investment.
Ultimately, the reported improvement suggests that South Africa’s office market is moving towards a more balanced position, but recovery remains selective. Buildings that match tenant requirements, control operating expenses and maintain strong locations are likely to be better placed to benefit.
Conclusion: South Africa’s declining office vacancy rate provides a positive signal for commercial real estate, yet the recovery is far from uniform. The key challenge for property owners and investors is to turn improved occupancy into durable financial performance through competitive buildings, responsible investment and a clear understanding of changing business needs.