


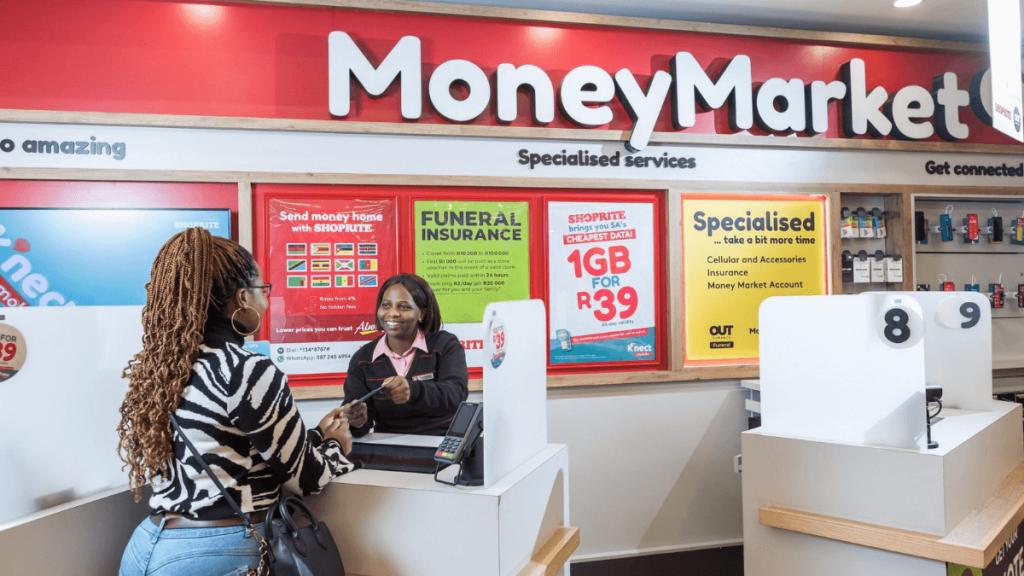
“Shoprite Holdings and Investec have agreed in principle to establish a banking partnership that will expand Shoprite Financial Services’ transactional account offering and introduce a debit card, subject to regulatory approval. The arrangement could make banking services more accessible through Shoprite’s retail network while allowing Investec to reach new customers and expand its participation in South Africa’s retail banking and payments markets.”
Shoprite and Investec Partnership Signals a New Era of Retail Banking in South Africa
Introduction
South Africa’s banking sector is entering another important phase of competition as retailers increasingly expand their involvement in financial services. On 9 November 2026, Shoprite Holdings and Investec announced an agreement in principle to establish a banking partnership that could significantly strengthen Shoprite Financial Services’ transactional banking offering. The proposed partnership includes the introduction of a debit card and an expanded transactional account, subject to regulatory approval.
The announcement represents a strategic development for both companies. Shoprite aims to improve access to affordable financial services for its customers, while Investec sees an opportunity to broaden its customer base beyond its traditional private banking market. The partnership also highlights the growing importance of retail distribution networks, digital payments and customer-focused financial products in South Africa.
Shoprite Expands Beyond Traditional Retail
Shoprite Holdings is South Africa’s largest grocery retailer, with a substantial presence across the country through its supermarket brands and associated retail operations. Although its core business remains grocery retailing, the company has increasingly explored opportunities to expand its financial services offering.
Retailers have several advantages when entering financial services. Their stores attract customers regularly, providing convenient locations for accessing products and services. In addition, established loyalty programmes, customer relationships and digital platforms can support financial service distribution.
Shoprite’s financial services strategy reflects this broader retail industry development. By expanding transactional banking services, the company can potentially improve customer engagement while creating additional opportunities to generate revenue beyond conventional grocery sales.
The proposed partnership with Investec is an important step in that direction.
Investec Provides Banking Infrastructure
Under the agreement announced on Monday, Investec is expected to become the banking sponsor for an expanded transactional account offered through Shoprite Financial Services.
Shoprite Financial Services will distribute banking products through Shoprite’s retail brands, physical stores and digital channels. Investec, meanwhile, will provide the banking licence, regulatory framework, balance sheet and infrastructure required to support the proposed banking arrangement.
This division of responsibilities allows the two companies to concentrate on their respective strengths.
Shoprite possesses an extensive retail distribution network and established customer relationships. Investec contributes banking expertise, regulatory capabilities and financial infrastructure.
The arrangement could therefore create a banking model in which customers interact with financial services through familiar retail channels while the underlying banking operations are supported by an established financial institution.
Debit Card Introduction Could Improve Customer Convenience
One of the most significant features of the proposed partnership is the planned introduction of a debit card.
Debit cards remain an important payment instrument for South African consumers, enabling purchases at retailers, online merchants and other businesses without requiring physical cash.
The expanded transactional account is expected to provide customers with additional payment options, improved security and access to broader digital payment services.
For consumers, the combination of a transactional account and debit card could provide greater flexibility when managing everyday expenses.
Customers may also benefit from having banking services distributed through locations they already visit for grocery shopping and other household purchases.
However, the companies have not announced all the detailed terms of the proposed account, including its complete pricing structure, eligibility requirements and final product specifications.
Consequently, customers should wait for official product announcements before making assumptions about account fees or specific banking benefits.
Financial Inclusion and Affordable Banking
Financial inclusion remains an important issue in South Africa, where consumers have different levels of access to banking products and digital financial services.
Although the country has an established banking industry, affordability, accessibility and customer experience continue to influence competition.
Shoprite has indicated that its financial services strategy aims to make banking more affordable and accessible to customers.
The retailer’s physical presence could be particularly relevant for customers who regularly visit its stores but may prefer banking services that are straightforward and convenient.
An expanded transactional account could potentially support everyday financial activities, including receiving payments, making purchases and managing household spending.
Nevertheless, affordability will ultimately depend on the final account structure, transaction charges and associated service conditions.
The partnership’s success will therefore depend not only on distribution but also on the value customers receive from the banking product.
Retailers Increasingly Compete in Financial Services
Shoprite’s announcement reflects a broader international trend in which major retailers develop financial services to complement their core businesses.
Retailers increasingly recognise that payment services, customer accounts and digital financial products can strengthen relationships with consumers.
Financial services may also generate additional customer engagement and provide opportunities to integrate shopping experiences with payment solutions.
South Africa has already witnessed significant developments in this area, with several retailers and financial institutions exploring partnerships, digital payment platforms and alternative banking models.
The Shoprite-Investec arrangement demonstrates how cooperation between retailers and established banks can support this transformation.
Instead of building every banking capability independently, a retailer can work with a regulated banking institution to develop and distribute financial products.
Such arrangements may reduce operational complexity while allowing the retailer to focus on customer experience and distribution.
Strategic Benefits for Investec
For Investec, the partnership presents an opportunity to expand beyond its traditional private banking customer base.
The bank has historically been associated with sophisticated financial services, wealth management and banking products for higher-income customers and businesses.
However, participation in a retail banking partnership could introduce Investec to a broader consumer market.
Investec Group Chief Executive Fani Titi indicated that the arrangement offers an opportunity to increase the group’s participation in South Africa’s payments ecosystem and retail deposit market.
The partnership could therefore support strategic diversification by connecting Investec’s banking infrastructure with Shoprite’s large retail customer base.
It may also provide opportunities to develop additional financial services as the partnership evolves.
Importantly, the agreement is non-exclusive. Shoprite and Investec have confirmed that the proposed alliance will not affect existing relationships with banks, payment providers, loyalty partners or other strategic partners.
This flexibility allows Shoprite to continue exploring financial services opportunities while maintaining its existing commercial relationships.
Digital Banking and Payment Competition
South Africa’s financial services industry continues to experience changes driven by mobile technology, digital payments and changing customer expectations.
Consumers increasingly expect banking services to be accessible through digital channels, with efficient transactions and straightforward account management.
The proposed Shoprite-Investec partnership is expected to expand access to digital payment services alongside the introduction of a debit card.
Combining physical stores with digital distribution may create a convenient customer experience.
For example, customers could potentially access information about financial products through retail channels and manage relevant transactions through digital services.
The precise digital capabilities of the expanded offering will depend on the products and features ultimately approved and launched.
The development nevertheless demonstrates that competition in banking increasingly involves customer access, payment infrastructure and distribution rather than traditional branch networks alone.
Regulatory Approval Remains Essential
Despite the announcement, the proposed partnership is not yet a fully operational banking arrangement.
The companies have agreed in principle, and the alliance remains subject to regulatory approval.
This distinction is important because banking products operate within a regulated environment designed to protect customers, maintain financial stability and ensure compliance with applicable requirements.
The approval process will determine whether the proposed structure can proceed as planned.
Until the necessary approvals are obtained and the companies formally launch the products, customers should not assume that the expanded transactional account or debit card is immediately available.
Additional announcements are expected to clarify the implementation process, product terms and launch arrangements.
Implications for South African Consumers
The partnership could have several implications for consumers if successfully implemented.
First, it may increase competition in the transactional banking market by introducing another retail-distributed financial services offering.
Second, it could improve convenience for customers who regularly use Shoprite stores and digital channels.
Third, it may encourage established banks to strengthen their own customer acquisition strategies, digital offerings and pricing structures.
However, competition does not automatically guarantee lower banking costs.
The eventual benefits will depend on account fees, transaction charges, customer service standards, digital functionality and the availability of suitable payment services.
Consumers should therefore compare the final Shoprite Financial Services offering with existing bank accounts before deciding whether to switch or open an additional account.
Conclusion
Shoprite Holdings and Investec’s proposed banking partnership represents a significant development in South Africa’s evolving financial services industry.
By combining Shoprite’s extensive retail distribution network with Investec’s banking infrastructure, the companies aim to expand transactional banking services, introduce a debit card and improve access to digital payments.
For Shoprite, the partnership strengthens its ambition to become a more comprehensive provider of consumer services.
For Investec, it creates an opportunity to reach customers beyond its traditional banking segments and participate more extensively in retail payments and deposits.
For South Africa’s banking industry, the announcement reinforces the growing importance of partnerships, digital channels and customer accessibility.
The immediate next step remains regulatory approval and the eventual launch of the expanded products. If implemented successfully, the alliance could contribute to stronger competition and greater convenience in South African transactional banking.
The partnership therefore deserves close attention from consumers, financial institutions, retailers and industry observers as South Africa’s banking market continues to evolve.