


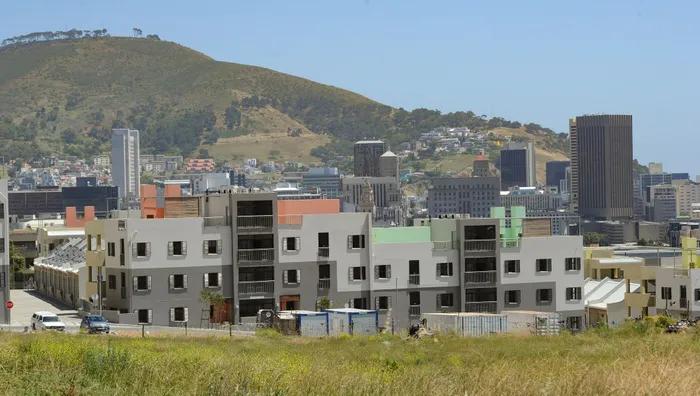
“Rising residential property prices in Cape Town are making homeownership increasingly difficult for first-time buyers, prompting young people and families to explore joint property purchases, smaller apartments and investment properties instead of traditional standalone homes. Property expert Rowan Alexander says shared ownership and micro-apartments are becoming alternative routes into the market, while improved municipal governance and service delivery could help strengthen residential property confidence in other major cities.”
Cape Town property prices reshape homeownership as buyers embrace joint investments and smaller apartments
Cape Town’s housing affordability challenge intensifies
Cape Town’s residential property market is increasingly forcing prospective homeowners to rethink how they enter the property sector. Rising property prices, limited affordability and the financial demands associated with purchasing a home are encouraging first-time buyers to consider alternatives to traditional homeownership.
A report published by Eyewitness News on 10 November 2026 highlights the growing popularity of joint property purchases, smaller apartments and shared investments among younger South Africans. The development reflects a broader transformation in how households approach residential property ownership, particularly in the Western Cape, where property values have continued to outperform several other metropolitan markets.
According to figures referenced in the EWN report, Cape Town recorded annual property price increases of approximately 12% in June 2026, compared with 4.9% in Johannesburg. These differences illustrate the increasingly uneven performance of South Africa’s metropolitan housing markets.
For first-time buyers, the consequences are significant. Purchasing a conventional family home in an established Cape Town suburb may require substantially greater financial resources than entering the market in other regions. Consequently, younger households are exploring different strategies to establish property ownership while managing their financial obligations.
First-time buyers confront an affordability barrier
Homeownership has traditionally represented a significant financial milestone for South African households. Owning a residential property provides security, long-term investment potential and an opportunity to accumulate wealth through property appreciation.
However, affordability remains a central obstacle for many first-time buyers.
Higher property prices increase the deposit required to secure mortgage finance. In addition, prospective homeowners must account for bond repayments, transfer costs where applicable, insurance, municipal rates, maintenance and other recurring expenses.
The situation becomes particularly challenging when household incomes do not increase at the same pace as property prices.
Cape Town’s sustained property demand has contributed to an environment in which some buyers struggle to purchase the homes they would prefer. As a result, homeownership decisions are increasingly influenced by affordability rather than lifestyle preferences alone.
Property expert Rowan Alexander, director of Alexander Swart Property Group, told 702 and CapeTalk that the difficulty facing middle-market first-time buyers has developed gradually over time.
His observations suggest that the affordability challenge is not simply a temporary market fluctuation. Instead, it reflects longer-term changes in the relationship between residential property prices, household incomes and purchasing power.
Joint ownership becomes an alternative entry strategy
One increasingly visible response is joint property ownership.
Instead of purchasing a residential property independently, buyers combine financial resources with relatives, partners or trusted investment partners. This arrangement can potentially increase purchasing power and make properties accessible that would otherwise be unaffordable to individual buyers.
Parents purchasing alongside their adult children represent one example of this strategy.
In some cases, parents and children jointly acquire a property designed to accommodate multiple generations. Such arrangements may provide housing for younger family members while offering retirement accommodation or long-term residential security for older relatives.
Another approach involves families purchasing an investment property together.
Rather than immediately buying a primary residence, young buyers may participate in the acquisition of a smaller apartment that generates rental income or offers exposure to property appreciation.
The strategy allows participants to begin building property-related wealth while continuing to rent their own accommodation.
Nevertheless, joint ownership requires careful financial planning.
Co-owners should establish clear agreements concerning ownership percentages, mortgage obligations, maintenance expenses, rental income, decision-making and eventual property sales.
Legal documentation is essential because financial disagreements or changes in personal circumstances can complicate jointly owned assets.
Smaller apartments create new investment opportunities
Compact residential apartments are also gaining attention as buyers search for more accessible entry points into Cape Town’s property market.
The EWN report describes micro-units measuring approximately 30 to 38 square metres, with examples priced around R2.5 million in certain repurposed buildings. These developments may be attractive to investors interested in short-term accommodation or rental opportunities.
Although such apartments offer relatively limited living space, they can provide an alternative to purchasing larger residential properties.
The appeal is particularly relevant to buyers who prioritise investment exposure over immediate occupation.
However, compact apartments are not automatically affordable investments. Buyers must evaluate the purchase price against potential rental income, operating expenses, financing costs and the property’s long-term resale prospects.
Location remains particularly important.
Apartments situated near employment centres, universities, transport infrastructure and commercial districts may attract stronger rental demand than properties in less accessible locations.
Investors must also investigate building management, security, maintenance standards and applicable municipal requirements.
Where short-term letting is involved, owners should understand building rules, relevant local regulations and the costs associated with managing accommodation.
Renting while investing changes the traditional ownership model
An important shift highlighted by Alexander concerns the separation between owning a property and living in it.
Historically, many households prioritised purchasing the residence in which they intended to live permanently. However, rising prices are encouraging some buyers to adopt a different financial approach.
Under this strategy, individuals rent their primary residence while investing in another property.
The reasoning is that purchasing a smaller investment apartment may be financially achievable even when acquiring a suitable family home is not.
Such an arrangement allows investors to participate in residential property markets while retaining flexibility regarding their living arrangements.
Nevertheless, the approach carries risks.
Rental income is not guaranteed, vacancies can reduce returns, and property ownership introduces ongoing expenses. Mortgage repayments may continue even when a tenant leaves or rental income falls below expectations.
Consequently, prospective investors should assess their ability to maintain repayments independently of rental income.
A carefully evaluated investment property may offer long-term advantages, but an unsuitable purchase can create significant financial pressure.
Residential property investment increasingly attracts younger buyers
The growing interest in joint purchases and smaller apartments demonstrates how younger South Africans are adapting to a changing residential property environment.
For many young professionals, purchasing a property independently shortly after entering employment may be unrealistic. Combining resources with other investors can create opportunities to enter the market earlier.
This trend could gradually influence the residential property sector’s development priorities.
Demand for compact apartments, flexible living arrangements and investment-oriented housing may encourage developers to consider different residential formats. Smaller units could appeal to investors, single professionals and buyers seeking more manageable property investments.
However, the sustainability of this trend depends on the relationship between purchase prices and rental demand.
Developers must ensure that new apartments respond to genuine housing needs rather than relying exclusively on speculative investment demand.
A healthy residential market should accommodate investors while also providing suitable homes for households seeking permanent accommodation.
Johannesburg illustrates the importance of municipal governance
Although Cape Town remains central to the affordability discussion, the EWN report also highlights the importance of municipal governance and service delivery in Johannesburg.
Alexander argued that improved governance, reliable municipal services and greater confidence could help support residential property values in Johannesburg and other Gauteng markets.
Municipal infrastructure plays a significant role in residential property attractiveness.
Reliable electricity, water supply, sanitation, roads, waste management and public safety influence where households choose to live and where investors are willing to purchase property.
Areas experiencing consistent infrastructure deterioration may face reduced buyer confidence, higher maintenance expenses and additional costs associated with private service alternatives.
Conversely, effective municipal administration can support neighbourhood stability, encourage investment and strengthen demand for residential developments.
The issue is particularly important for South Africa’s major metropolitan areas, where housing affordability intersects with urban infrastructure challenges.
Residential property values cannot be evaluated exclusively through building characteristics or market demand. The surrounding neighbourhood and quality of municipal services remain fundamental considerations.
Regional property differences are becoming increasingly significant
Cape Town’s residential market illustrates the importance of regional differences in property investment.
While the Western Cape has experienced relatively strong price growth, other metropolitan markets may offer different opportunities for buyers.
Johannesburg, Pretoria, Durban and selected secondary cities have their own demand patterns, affordability conditions and infrastructure considerations.
For first-time buyers, comparing locations can reveal alternatives to purchasing within the most expensive neighbourhoods.
However, relocating to a lower-priced market does not automatically guarantee a better investment.
Employment opportunities, transport expenses, access to essential services and future property demand should all be considered before purchasing.
Buyers should evaluate total housing costs rather than focusing exclusively on the purchase price.
A relatively inexpensive property located far from employment centres may create additional commuting expenses that reduce its financial advantages.
What the changing market means for prospective homeowners
The developments highlighted by EWN offer several important lessons for South African residential property buyers.
First, prospective homeowners should establish realistic budgets before searching for properties.
Mortgage affordability depends on income, existing debt, interest rates and lender requirements. Buyers should also account for the additional expenses associated with property ownership.
Second, alternative ownership structures should be evaluated carefully.
Joint purchases can expand purchasing power, but they require transparent agreements and a clear understanding of financial responsibilities.
Third, buyers should distinguish between purchasing a home for occupation and purchasing property as an investment.
The two objectives may require different strategies, financial calculations and risk assessments.
Finally, prospective homeowners should avoid assuming that property prices will always rise sufficiently to compensate for an expensive purchase.
Residential property remains a long-term asset that can experience periods of weaker demand, slower appreciation or declining values in particular locations.
Outlook for South Africa’s residential property market
Cape Town’s affordability challenges are likely to remain an important issue in discussions about residential property access.
The growing popularity of joint purchases, smaller apartments and investment-oriented ownership reflects the financial adjustments households are making in response to rising housing costs.
These strategies may offer opportunities for some buyers, but they cannot independently resolve the broader shortage of affordable housing.
Sustainable improvements will also require an expansion of housing supply, appropriate infrastructure investment, stronger employment opportunities and residential development that responds to the needs of different income groups.
For developers, the challenge will be to deliver housing that balances commercial viability with genuine affordability.
For policymakers, improving access to housing will require coordination between municipal authorities, financial institutions, developers and communities.
For buyers, careful financial planning and informed investment decisions will become increasingly important.
Cape Town’s property market demonstrates that the traditional pathway to homeownership is evolving. Increasingly, South Africans are exploring shared financial commitments, smaller properties and investment purchases as they seek to participate in residential real estate.
The changing landscape does not necessarily mean that homeownership is disappearing. Rather, it suggests that the route towards owning property is becoming more diverse, financially demanding and dependent on individual circumstances.
Ultimately, the ability of South Africa’s residential market to remain inclusive will depend on whether housing supply, household incomes and property prices can move towards a more sustainable balance.
Conclusion: A new pathway to property ownership
Cape Town’s residential property market is increasingly encouraging first-time buyers to rethink traditional homeownership. Joint investments, family partnerships and smaller apartments are becoming practical alternatives for households unable to purchase conventional residential properties independently.
While these approaches create new opportunities, affordability remains a significant challenge. The long-term sustainability of residential property ownership will depend on improved housing supply, stronger household purchasing power and effective municipal governance.
The developments reported on 10 November 2026 demonstrate that South Africa’s residential property market is not simply changing in terms of prices. It is also changing how people approach ownership, investment and housing security.