


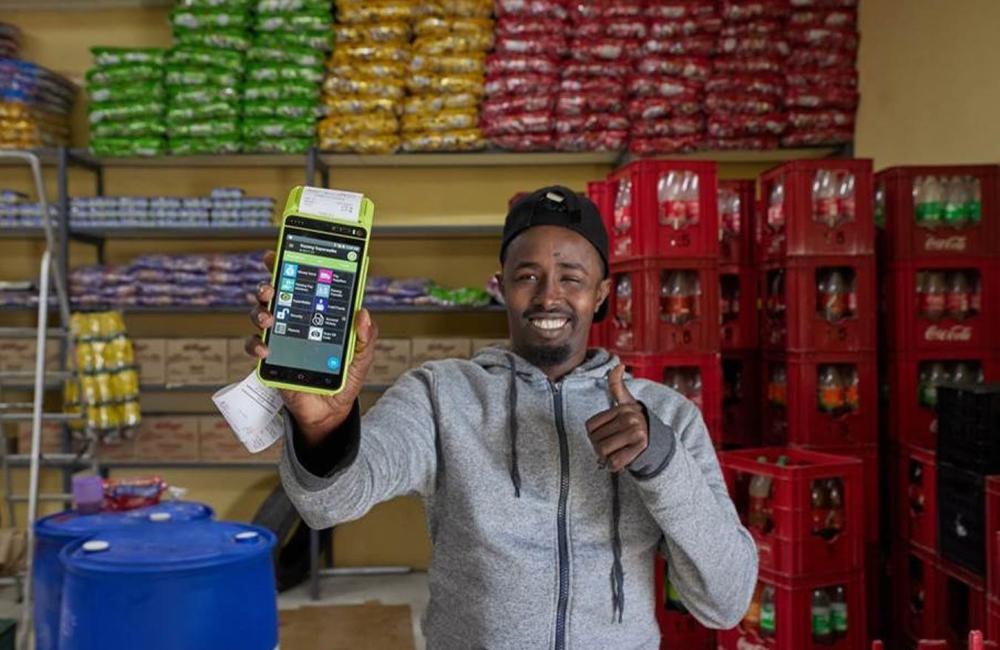
“South Africa plans to allow non-bank businesses, including telecommunications operators, fintech companies and retailers, to connect directly to the national payments infrastructure from mid-2027, ending their traditional dependence on banks as intermediaries. The South African Reserve Bank says the reform is intended to increase competition, reduce transaction costs, expand digital financial inclusion and encourage innovation, with further regulatory details expected in November 2026.”
South Africa’s Payments Policy Reform Could Reshape Business Competition and Digital Finance
Introduction: A major shift in the business-policy environment
South Africa is preparing for a significant change in the regulation of its financial services industry, with plans to open the national payments system to eligible non-bank businesses from mid-2027. The reform will allow companies such as fintech providers, telecommunications operators and retailers to connect directly to the country’s payment infrastructure rather than relying exclusively on banks to facilitate their participation.
The announcement, reported by Reuters on 16 October 2026, represents an important development in the government’s broader efforts to modernise the economy, encourage competition and improve access to digital financial services. The South African Reserve Bank (SARB) is leading the Payments Ecosystem Modernisation (PEM) programme, which seeks to make the payments industry more inclusive, efficient and innovative.
For businesses, the proposed changes could influence how money moves between customers, merchants and financial service providers. For consumers, they could create opportunities for more accessible payment products and potentially lower transaction costs. However, the eventual benefits will depend on the regulatory requirements, implementation timetable, technology investments and safeguards established by the authorities.
What the proposed payments reform means
South Africa’s national payments infrastructure supports the movement of money between financial institutions and enables transactions to be cleared and settled. Traditionally, banks have occupied a central position in this system, providing essential connections and services to other organisations that want to participate in payment activities.
Under the proposed reform, eligible non-bank providers will be able to access relevant payment infrastructure directly, subject to the applicable regulatory framework. This would create additional opportunities for fintech businesses, retailers and telecommunications companies to develop and deliver payment services.
The policy change is part of a wider effort to move towards an activity-based regulatory model. Under such a model, regulatory requirements are designed around the payment activities a company performs, rather than relying solely on whether the company is classified as a traditional bank.
The Reserve Bank’s modernisation programme identifies direct participation by non-banks as an important means of establishing a more level playing field, encouraging innovation and improving efficiency. The programme also encompasses changes to licensing and authorisation arrangements and the development of the broader legal framework governing payments.
This does not mean that every retailer or technology company will automatically be authorised to handle payments. Businesses will still need to meet the relevant requirements, and the precise conditions will depend on the final rules.
Why the government wants greater competition
Competition is a central objective of the proposed reform. When access to essential infrastructure depends on established intermediaries, smaller providers may face additional costs, operational complexity or commercial constraints when attempting to introduce new services.
Allowing qualified non-bank providers to connect directly could give them greater control over payment processing and product development. It could also reduce their dependence on arrangements with established financial institutions.
For example, a fintech company developing a digital payment application may be able to design services around its own technology and customer relationships without relying on precisely the same intermediary arrangements as before. A retailer could explore more integrated payment services, while a telecommunications operator could build on its existing mobile platforms to reach customers who have limited access to traditional banking channels.
Nevertheless, direct access will not automatically eliminate every fee or guarantee cheaper transactions. Providers will still need to pay for technology, security, compliance, customer support and other operational requirements. Whether savings reach businesses and consumers will depend on market competition and the pricing decisions of individual providers.
The reform’s success should therefore be measured not simply by the number of new companies entering the system, but by whether competition produces better services, transparent fees and meaningful improvements in customer choice.
Opportunities for small businesses and retailers
Small and medium-sized enterprises are among the groups that could benefit from a more competitive payments environment.
For many small businesses, accepting digital payments is important for reaching customers who prefer electronic transactions. However, payment-related expenses and the practical challenges of adopting new technology can affect profitability, especially for businesses operating on narrow margins.
If the reform encourages more providers to compete for merchants, small businesses could gain access to alternative payment products, more flexible service packages and improved transaction management tools. Some providers may also combine payments with accounting, stock management or digital sales platforms.
Retailers could potentially benefit from more integrated systems connecting online stores, physical outlets and customer loyalty programmes. Meanwhile, service businesses could have additional choices for collecting payments and managing transactions.
These outcomes are possibilities rather than guaranteed results. The new policy will need to produce genuine commercial competition, and providers must make their products accessible to smaller merchants rather than concentrating exclusively on large companies.
Small businesses should consequently assess the full cost of any payment service, including setup fees, transaction charges, settlement periods, equipment expenses and contractual restrictions.
Telecommunications companies and fintech innovation
Telecommunications operators have established distribution networks and digital platforms that could help them expand their financial services offerings. Mobile connectivity can provide an important channel for reaching customers who may be underserved by conventional financial institutions.
Fintech companies, meanwhile, often specialise in developing payment applications, digital wallets, merchant services and automated transaction systems. Direct access to the payments infrastructure could give eligible providers additional opportunities to compete and scale their operations.
South Africa’s payments reform may therefore encourage new partnerships between technology businesses, retailers and financial service providers. It could also stimulate investment in fraud prevention, identity verification, payment interfaces and other supporting technologies.
However, the ability to compete will depend on more than market access. Companies must demonstrate operational resilience, protect customer information, manage cyber risks and comply with the relevant financial regulations.
The Reserve Bank will face the challenge of encouraging innovation while ensuring that new participants meet appropriate standards. Its modernisation programme explicitly recognises the importance of improving the payments ecosystem while maintaining financial stability and reducing risks.
Regulatory details and the 2027 implementation timetable
The implementation process will be critical to the reform’s effectiveness.
Reuters reported that the Reserve Bank expected to publish rules governing payment activities and exemptions by November 2026. The first non-bank participants are expected to begin operating around March 2027 following testing, ahead of the wider mid-year opening.
These stages matter because payment systems require extensive coordination. Participants must establish technical connections, test transaction processing, demonstrate operational readiness and comply with applicable authorisation conditions.
The rules will also need to clarify which activities require specific permissions and what obligations providers must meet. Clear requirements can help businesses prepare investment plans, while transparent approval procedures can reduce uncertainty for prospective entrants.
For the regulator, the challenge will be to ensure that the framework is proportionate. Requirements that are too restrictive could discourage responsible entrants, while insufficient safeguards could expose consumers and the financial system to unnecessary risks.
Businesses considering entry should monitor official Reserve Bank announcements rather than treating the proposed timetable as permission to begin regulated activities immediately.
Financial inclusion and access to digital services
Financial inclusion is another important policy objective.
Access to affordable and reliable payment services can help individuals participate in the formal economy and enable small enterprises to transact with a wider customer base. Digital services may also make it easier for people to receive money, pay bills and conduct everyday transactions without relying entirely on physical cash.
A more open payments environment could encourage providers to develop products for customers whose needs are not adequately addressed by existing services. Competition could also support improvements in convenience, accessibility and the range of available payment channels.
Nevertheless, digital inclusion involves more than allowing additional companies into the market. Consumers need reliable connectivity, suitable devices, accessible customer support and confidence that their money and personal information are protected.
People with limited digital literacy or inconsistent access to technology may still experience barriers. Cash will therefore remain relevant, particularly for communities where digital infrastructure and connectivity are less reliable.
The Reserve Bank’s wider modernisation programme includes initiatives intended to improve payment efficiency and access. Its longer-term impact will depend on how these measures work together and whether providers develop services that meet the needs of underserved communities.
Cash infrastructure and the future of payments
The proposed reforms extend beyond competition between digital payment providers. Reuters also reported plans involving a national cash utility and shared, or white-label, automated teller machines.
These initiatives are intended to address the costs associated with cash handling while helping preserve access to cash, including in rural areas. According to the report, an ATM pilot is planned for January 2027, with a broader rollout anticipated by the end of that year.
The policy direction recognises that modernising payments does not require the immediate disappearance of physical money. Cash remains important for consumers and businesses that depend on it, and its availability can be especially significant in communities with limited banking infrastructure.
Shared infrastructure could potentially help reduce duplication and improve the economics of maintaining cash services. However, its success will depend on implementation costs, geographic coverage, service reliability and whether the arrangements are commercially sustainable.
Taken together, the digital and cash-related initiatives indicate that the Reserve Bank is pursuing a broader redesign of how payments are delivered across the economy.
Risks, consumer protection and financial stability
Opening the payments system to more participants will also introduce challenges.
First, the regulator will need to ensure that new entrants maintain appropriate security standards. Payment systems are attractive targets for fraud and cybercrime, and an increase in participants can create additional points of vulnerability if controls are inadequate.
Second, customers need clear information about fees, transaction disputes, refunds and the responsibilities of different providers. If something goes wrong, consumers should be able to understand where to seek assistance and how complaints will be resolved.
Third, operational failures at a payment provider could interrupt services for merchants and customers. Providers will therefore need suitable contingency plans, dependable technology and effective risk management.
Finally, competition must remain fair. Direct access will be meaningful only if the requirements are transparent and qualified businesses have a reasonable opportunity to participate.
The Reserve Bank will need to balance these concerns with the goal of reducing unnecessary barriers to innovation. Strong supervision and predictable rules can support competition by building trust in the system rather than undermining it.
What businesses should do now
Businesses should use the period before implementation to assess how the proposed changes could affect their operations.
Retailers and small enterprises can review their current payment costs, identify service limitations and compare the features they would need from alternative providers. They should also examine settlement times, customer support arrangements and the security measures offered by prospective partners.
Fintech companies and telecommunications operators should monitor the forthcoming licensing rules, assess the technical requirements for participation and determine whether they have the expertise and capital needed to operate responsibly.
Investors should distinguish between the commercial opportunity created by policy reform and the financial performance of individual companies. Greater market access may create new opportunities, but it does not guarantee profitability or eliminate regulatory and operational risks.
Industry associations can also contribute by helping smaller businesses understand the new arrangements and identifying practical obstacles that might otherwise limit adoption.
Conclusion: A potential turning point for South African business policy
South Africa’s plan to open its national payments system to eligible non-bank businesses represents a significant proposed shift in the organisation of the financial services industry. By enabling greater direct participation from fintech companies, retailers and telecommunications operators, the reform could create opportunities for innovation, competition and broader access to digital payments.
Its importance extends beyond the banking sector. More accessible and efficient payments could help small businesses serve customers, encourage new financial products and support wider participation in the formal economy.
However, the outcome will depend on how the policy is implemented. Clear licensing rules, effective consumer protection, secure infrastructure and genuine competition will be essential if the intended benefits are to reach businesses and households.
The November 2026 regulatory announcements and the expected 2027 rollout will be important milestones to watch. Until the final requirements and commercial effects become clearer, businesses should prepare carefully while avoiding assumptions that lower fees or universal access are already assured.
Ultimately, the reform’s success will be determined by whether it creates a payments environment that is more competitive, secure, affordable and inclusive for South Africans.