




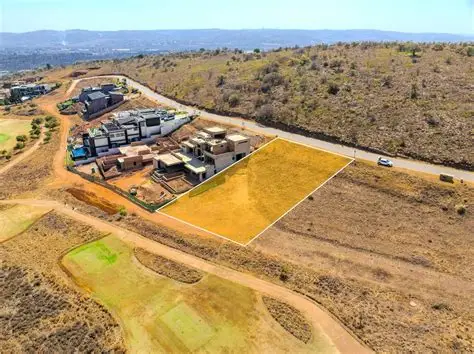
“South Africa’s property market in August 2026 reflects resilience, with land and housing prices growing steadily across key regions despite inflationary pressures. Demand for affordable housing and semigration to coastal provinces continues to drive land transactions, while stable interest rates provide predictability for investors.”
The South African land and real estate market in August 2026 is navigating a complex but promising landscape. With the national average property price growth ranging between 5–7% year-on-year, the sector is buoyed by strong demand in affordable housing, semigration trends, and international investment. At the same time, inflationary pressures and cautious monetary policy from the South African Reserve Bank (SARB) temper expectations, creating a nuanced environment for buyers, sellers, and investors.
Interest Rate Stability and Market Confidence
The SARB has maintained the repo rate at 7.00% and the prime lending rate at 10.50%, a decision that has provided predictability in borrowing costs. This stability has reassured both buyers and developers, allowing for more measured investment decisions. Banks such as Absa, FNB, Standard Bank, and SA Home Loans are offering competitive mortgage packages, further stimulating activity in the land and housing market.
Land Transactions and Regional Dynamics
- Western Cape: Semigration from Gauteng and KwaZulu-Natal continues to fuel demand for land and housing. Cape Town remains the premium market, with average property prices at R3.35 million, far above the national average of R1.95 million.
- Garden Route (George, Knysna): Land values are appreciating at 6.5% annually, driven by lifestyle appeal and migration from inland provinces.
- Gauteng: While average growth is modest at 2.8%, certain nodes are experiencing niche expansion, particularly in mixed-use developments and industrial land.
Affordable Housing and Land Demand
The affordable housing segment (below R1.2 million) remains the most active, with demand consistently outstripping supply. First-time buyers, particularly younger South Africans aged 25–34, are entering the market with confidence levels reaching 90%, signaling a generational shift in land and property ownership. This has led to increased competition for vacant plots in peri-urban areas, where developers are racing to meet demand.
International Investment in Land
Foreign buyers from Europe and Asia are increasingly investing in South African land, particularly coastal properties. Favorable exchange rates and lifestyle appeal make South Africa an attractive destination for long-term investment. This trend has boosted land values in areas such as Durban, Cape Town, and the Garden Route, where international demand complements local semigration.
Inflationary Pressures and Risks
Despite nominal growth, headline inflation reached 5% in June 2026, reducing real returns to just 0.2%. Rising costs of construction materials and energy are eroding profitability for developers. Investors are cautious, balancing the strong demand for land with concerns about long-term affordability and economic volatility.
Structural Economic Signals
- Housing Index: 125.20 (Feb 2026)
- FDI Inflows: R20.3 billion in Q1 2026, with significant allocations to mining, energy, and finance.
- Unemployment: 32.7% in Q1 2026, underscoring the broader economic challenges that could impact land affordability.
Conclusion
South Africa’s land and real estate sector in August 2026 is characterized by steady growth, regional divergence, and cautious optimism. While semigration and affordable housing demand continue to drive land transactions, inflationary pressures and cautious monetary policy temper expectations. For investors and buyers, the current environment offers both opportunities and risks, requiring strategic decision-making and careful financial planning.



