




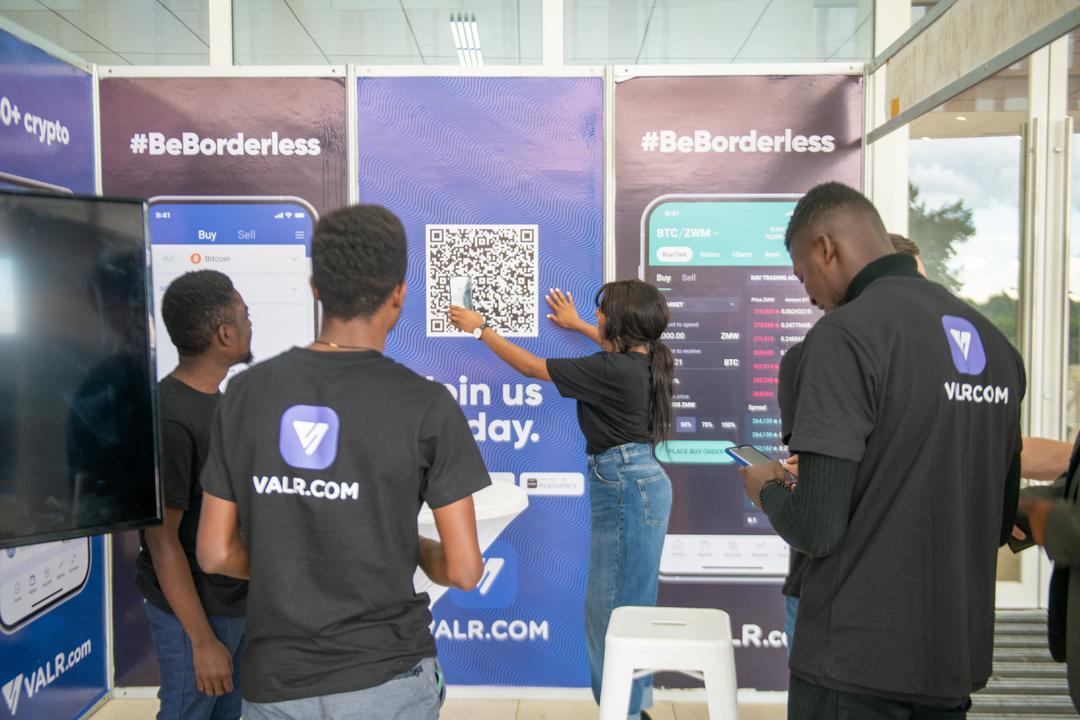
“First National Bank (FNB) has entered South Africa’s retail cryptocurrency market through a partnership with locally founded digital-asset exchange VALR, allowing customers to trade selected cryptocurrencies from as little as R10 through the bank’s existing investment platform. The move is significant because it brings cryptocurrency closer to mainstream banking customers while reflecting a broader shift among South African banks toward regulated digital assets, blockchain-based services and alternative investments.”
FNB’s Crypto Move Signals a New Era for South African Banking
South Africa’s banking industry is moving further into the digital-asset economy as First National Bank (FNB) launches cryptocurrency investing for its customers, marking another important step in the country’s rapidly changing financial-services landscape.
FNB has partnered with South African cryptocurrency exchange VALR to allow customers to buy and trade a selected range of digital assets through the bank’s existing share-trading infrastructure. The service gives customers exposure to Bitcoin, Ethereum, Ripple (XRP), Solana and USDT, a stablecoin designed to track the value of the US dollar.
The development is important well beyond the individual products being offered. It demonstrates how cryptocurrency, once treated by many traditional financial institutions as a marginal or potentially disruptive technology, is increasingly being incorporated into mainstream banking and investment services.
FNB customers can access the cryptocurrency offering through its existing Share Saver, Share Builder, Share Investor and Share Zero products. Trading is available around the clock, while the minimum investment has been set at only R10.
The low entry point is particularly significant because it potentially opens digital-asset exposure to ordinary retail investors rather than limiting participation to wealthy or technologically sophisticated customers.
FNB Responds to Growing Customer Demand
FNB executives say the introduction of cryptocurrency investing is largely a response to customer demand for alternative investment opportunities.
Sizwe Nxedlana, CEO of FNB and RMB Private Banking and Wealth Management, said customers would receive access to a curated selection of crypto assets while benefiting from FNB’s investment knowledge and experience.
Bheki Mkhize, CEO of FNB Wealth and Asset Management, similarly said the bank had observed substantial activity and interest among its customers around cryptocurrency.
That demand is taking place against a backdrop of rapidly increasing cryptocurrency adoption in South Africa. Data published by the South African Reserve Bank showed that registered customers at three major local crypto-asset service providers — Luno, VALR and Ovex — had increased to about 7.8 million by 2025, compared with approximately 6.6 million in 2024.
The same Reserve Bank data showed that the value of crypto assets held in custody by the three platforms had grown substantially, reaching about R25.2 billion at the end of 2024. Bitcoin accounted for the largest portion, followed by XRP and Ethereum.
For FNB, therefore, entering the market represents an attempt to meet customers where they already are rather than leaving digital-asset investing entirely to specialist exchanges.
A Carefully Controlled Cryptocurrency Model
Although FNB is embracing cryptocurrency, the bank has not simply opened unrestricted access to the broader crypto ecosystem.
Instead, the service has been deliberately ring-fenced within the FNB environment.
Customers can use funds held in their FNB accounts to purchase the supported crypto assets, but the cryptocurrency cannot be transferred into or out of the FNB platform. In other words, customers cannot move their crypto holdings to an external personal wallet or another cryptocurrency exchange through this service.
FNB says this structure is intended to provide greater platform security while taking a conservative approach to compliance and exchange-control requirements.
That approach is important because cryptocurrency remains a complicated regulatory area. Traditional banks must balance customer demand for digital assets with requirements relating to anti-money-laundering controls, financial crime prevention, consumer protection, taxation and exchange controls.
The ring-fenced model gives FNB greater control over transactions while still providing customers with exposure to cryptocurrency price movements.
It also distinguishes FNB’s offering from some competing models.
Discovery Bank, for example, introduced cryptocurrency trading through a partnership with Luno. Its model allows customers to connect their Luno account through the banking environment, creating a somewhat different relationship between the bank and the external crypto platform.
South African Banks Are No Longer Ignoring Crypto
FNB’s decision is part of a wider transformation across South Africa’s banking sector.
For years, cryptocurrency was viewed cautiously by major financial institutions. Banks were concerned about fraud, money laundering, volatility and the absence of clearly established regulatory structures.
That position is changing.
Discovery Bank has already moved into retail cryptocurrency trading, while Nedbank has explored blockchain-related payment, settlement and liquidity solutions through its partnership with Crypto.com. Absa has developed institutional digital-asset custody capabilities with Ripple, while Standard Bank has also been involved in digital-asset and stablecoin initiatives.
The different approaches demonstrate that banks are not necessarily treating cryptocurrency as a single product.
Instead, digital assets are becoming relevant to several areas of financial services.
For retail customers, the focus is investment and trading. For institutional clients, the emphasis may be custody and asset management. Meanwhile, banks are also investigating blockchain technology for payments, settlement, tokenised deposits and cross-border transactions.
This suggests that the future of banking may involve considerably more than simply allowing customers to buy Bitcoin.
Why the R10 Minimum Matters
One of the most notable elements of FNB’s announcement is the R10 minimum investment.
A low minimum means customers do not need substantial capital to experiment with cryptocurrency. Someone who is interested in digital assets can gain exposure without committing thousands of rand.
This could contribute to greater financial participation in alternative assets, particularly among younger consumers who are already familiar with digital financial services.
However, accessibility also creates a responsibility for banks to educate customers.
Cryptocurrency prices can be highly volatile. A low barrier to entry does not eliminate investment risk, and customers could lose money if the value of their chosen asset falls.
FNB has therefore indicated that educational material will form part of the offering. The bank plans to provide customers with learning resources covering the cryptocurrency market, investment risks and the characteristics of digital assets.
This educational component could become increasingly important as traditional financial institutions bring crypto products to a much wider audience.
Bitcoin Is Not the Only Focus
Although Bitcoin remains the best-known cryptocurrency, FNB’s selection demonstrates that the bank is taking a broader approach.
The initial offering includes Bitcoin, Ethereum, XRP, Solana and USDT.
Bitcoin is generally regarded as the largest and most established cryptocurrency by market recognition. Ethereum has a major role in blockchain applications, while XRP is associated with digital-payment infrastructure. Solana has developed a large ecosystem around blockchain applications, and USDT is a stablecoin designed to maintain a value linked to the US dollar.
For retail investors, this creates a basic level of diversification within the digital-asset category.
Nevertheless, diversification within cryptocurrencies is not equivalent to diversification across completely different asset classes. Digital assets can remain highly volatile and can experience sharp price movements.
Consequently, customers will need to understand the difference between investing in crypto and investing in traditional assets such as shares, bonds, money-market instruments or cash.
Regulation Will Remain Central
The expansion of banking into cryptocurrency also places greater importance on regulation.
South Africa has been developing a more formal regulatory framework for crypto-asset service providers, moving away from an environment in which cryptocurrency largely operated outside traditional financial regulation.
The growing involvement of established banks could strengthen consumer confidence, but it also raises expectations around transparency and investor protection.
FNB’s decision to keep cryptocurrency transactions inside its own ecosystem reflects this cautious regulatory environment.
The bank can establish controls over funding, trading and custody rather than allowing customers to move assets freely across the broader cryptocurrency ecosystem.
That could reduce certain operational risks, although it does not remove the fundamental investment risks associated with crypto prices.
What the Move Means for Traditional Banks
FNB’s entrance could also intensify competition within South African banking.
Once a major bank demonstrates that customers are interested in cryptocurrency investing, competitors may face greater pressure to introduce comparable services.
The competition could eventually extend beyond simply offering Bitcoin purchases.
Banks may begin competing over crypto custody, stablecoin payments, tokenised assets, blockchain-based international transfers and digital investment products.
This would represent a significant transformation because traditional banks would increasingly become gateways between conventional money and digital financial networks.
For customers, competition could result in more choice, lower fees, improved educational resources and better-integrated digital financial services.
For banks, however, it will require significant investment in technology, cybersecurity, compliance and risk management.
The Bigger Banking Transformation
FNB’s cryptocurrency launch should therefore not be viewed merely as another banking-app feature.
It is part of a broader transformation in how financial institutions think about money, investment and technology.
South Africa already has a sophisticated digital banking market, with consumers increasingly comfortable using mobile applications for payments, investments and everyday financial management.
The next stage could see banking platforms become gateways to a much wider range of financial assets.
Cryptocurrency is one part of that evolution.
Blockchain technology could eventually support faster settlement, tokenised securities, digital currencies and more efficient cross-border payments. Stablecoins could also play a role in international commerce and remittances if regulatory frameworks allow their use to expand.
For now, FNB is taking a measured approach. The bank has started with five assets, a R10 minimum investment and a ring-fenced system, while promising additional investment options and educational material in the future.
What Customers Should Watch
For South African consumers, the development creates an opportunity but also requires caution.
Customers considering the service should understand that cryptocurrency remains a volatile investment. The convenience of purchasing digital assets through a familiar bank does not mean those assets carry the same risk profile as a savings account or conventional bank deposit.
The ring-fenced structure also means that customers should understand exactly what rights and capabilities they receive through the FNB platform, particularly because the crypto assets cannot currently be transferred into or out of the system.
Investors should therefore consider their objectives, risk tolerance and investment horizon before committing money.
Conclusion
FNB’s decision to introduce cryptocurrency investing is one of the most important recent developments in South African banking because it brings digital assets directly into the country’s mainstream banking environment.
Through its partnership with VALR, FNB customers can access Bitcoin, Ethereum, XRP, Solana and USDT from R10 through existing FNB investment products.
The launch reflects growing customer demand, increasing cryptocurrency adoption and the broader evolution of South Africa’s regulatory and financial-technology environment.
More importantly, it shows that the relationship between traditional banking and cryptocurrency is changing. Banks that once largely avoided digital assets are now exploring ways to provide controlled access, custody, investment products and blockchain-based financial infrastructure.
FNB’s approach remains deliberately conservative, with crypto trading confined to its ecosystem and assets unable to be transferred externally. Nevertheless, the direction is clear: cryptocurrency is moving closer to mainstream South African banking.
The significance of the development may ultimately be measured not by how many customers buy Bitcoin through FNB, but by what comes next. If customer demand continues to grow, the country’s major banks could increasingly compete in digital assets, tokenised finance, stablecoins and blockchain-powered payments.
For South Africa’s banking industry, the crypto era is no longer a distant possibility. It has entered the mainstream banking conversation.



