




“The South African Reserve Bank (SARB) has kept the repo rate unchanged at 7.25%, citing global oil supply disruptions and domestic economic contraction as key risks. Inflation is expected to rise above 5% in late 2026 before stabilizing near the 3% target by 2027. “
South Africa’s banking sector and broader economy are once again under the spotlight following the Monetary Policy Committee (MPC) statement released on 30 September 2026. The SARB’s decision to hold the repo rate steady at 7.25% reflects a delicate balancing act between global inflationary pressures and domestic growth challenges.
Global Context
The MPC highlighted escalating Middle East conflicts, disruptions in oil exports through the Strait of Hormuz, and interruptions in Saudi supply due to fighting in Yemen. Combined with the ongoing Russia-Ukraine war, these factors have created a persistent global supply shock. The result has been higher fuel costs worldwide, with ripple effects reaching South Africa.
- Global interest rates rising: The US Federal Reserve hiked rates for the first time in three years, while the ECB and Bank of Japan also tightened policy.
- Fiscal deficits and AI infrastructure borrowing: Longer-term yields are climbing globally, reflecting structural imbalances.
Domestic Economic Performance
South Africa’s economy contracted by 0.2% in Q2 2026, following modest growth of 0.4% in Q1. The contraction was driven by weakness in trade, manufacturing, and mining, though household consumption remained resilient.
- Annual growth projection: 1.2% for 2026, with medium-term growth expected around 2% if reforms succeed.
- Risks skewed to the downside: Persistent global shocks and domestic structural challenges weigh heavily on forecasts.
Inflation Outlook
Fuel prices are the primary driver of near-term inflationary pressure. Petrol under-recoveries averaged R2.83 per litre, pushing headline inflation expectations above 5% in late 2026 and early 2027.
- Food inflation: At its lowest since 2010, offering some relief.
- Rand resilience: The currency has helped contain import costs despite global volatility.
- Medium-term forecast: Inflation expected to return to 3% by end-2027.
Banking Sector Implications
The SARB’s stance has direct consequences for South Africa’s major banks:
- Credit affordability: Higher rates strain household and business borrowing capacity.
- Net interest margins: Banks benefit from higher lending rates but face risks of rising defaults.
- Consumer resilience: Household consumption remains a bright spot, supporting retail banking activity.
Policy Significance
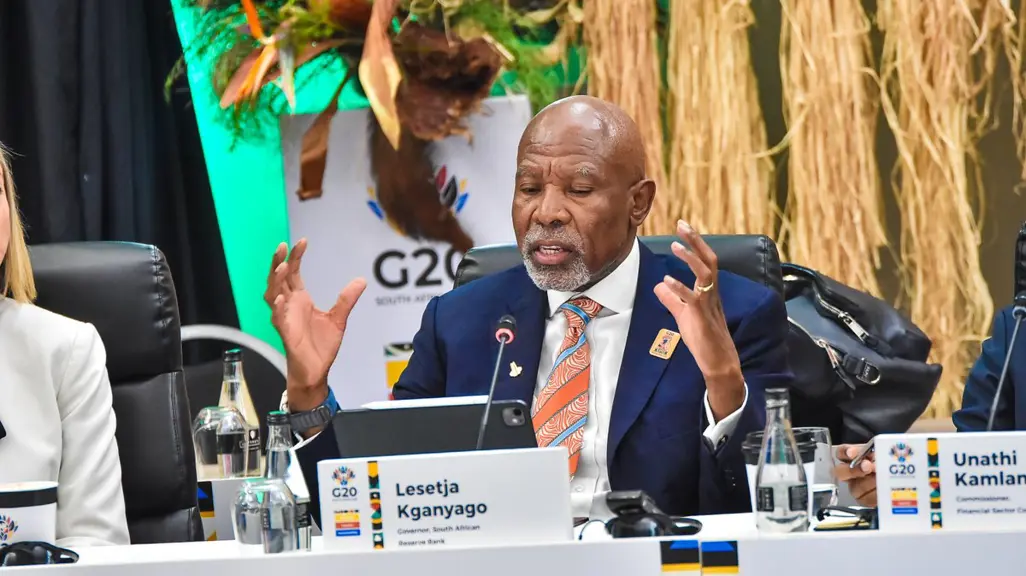
Governor Lesetja Kganyago emphasized that the SARB remains committed to its inflation-targeting mandate, even as growth risks mount. The decision reflects a cautious approach: tightening too aggressively could deepen recessionary pressures, while easing prematurely could entrench inflation.
Broader Market Reaction
- Bond yields: South African yields rose in line with global benchmarks.
- Equities: Banking stocks showed mixed performance, reflecting both margin benefits and credit risk concerns.
- Currency: The rand’s resilience continues to be a stabilizing factor, though volatility remains likely.
Conclusion
The SARB’s September 2026 MPC statement underscores the fragility of South Africa’s economic recovery. With global oil shocks, geopolitical instability, and domestic contraction weighing heavily, the central bank’s cautious stance is aimed at preserving stability while awaiting reforms to unlock growth.



