




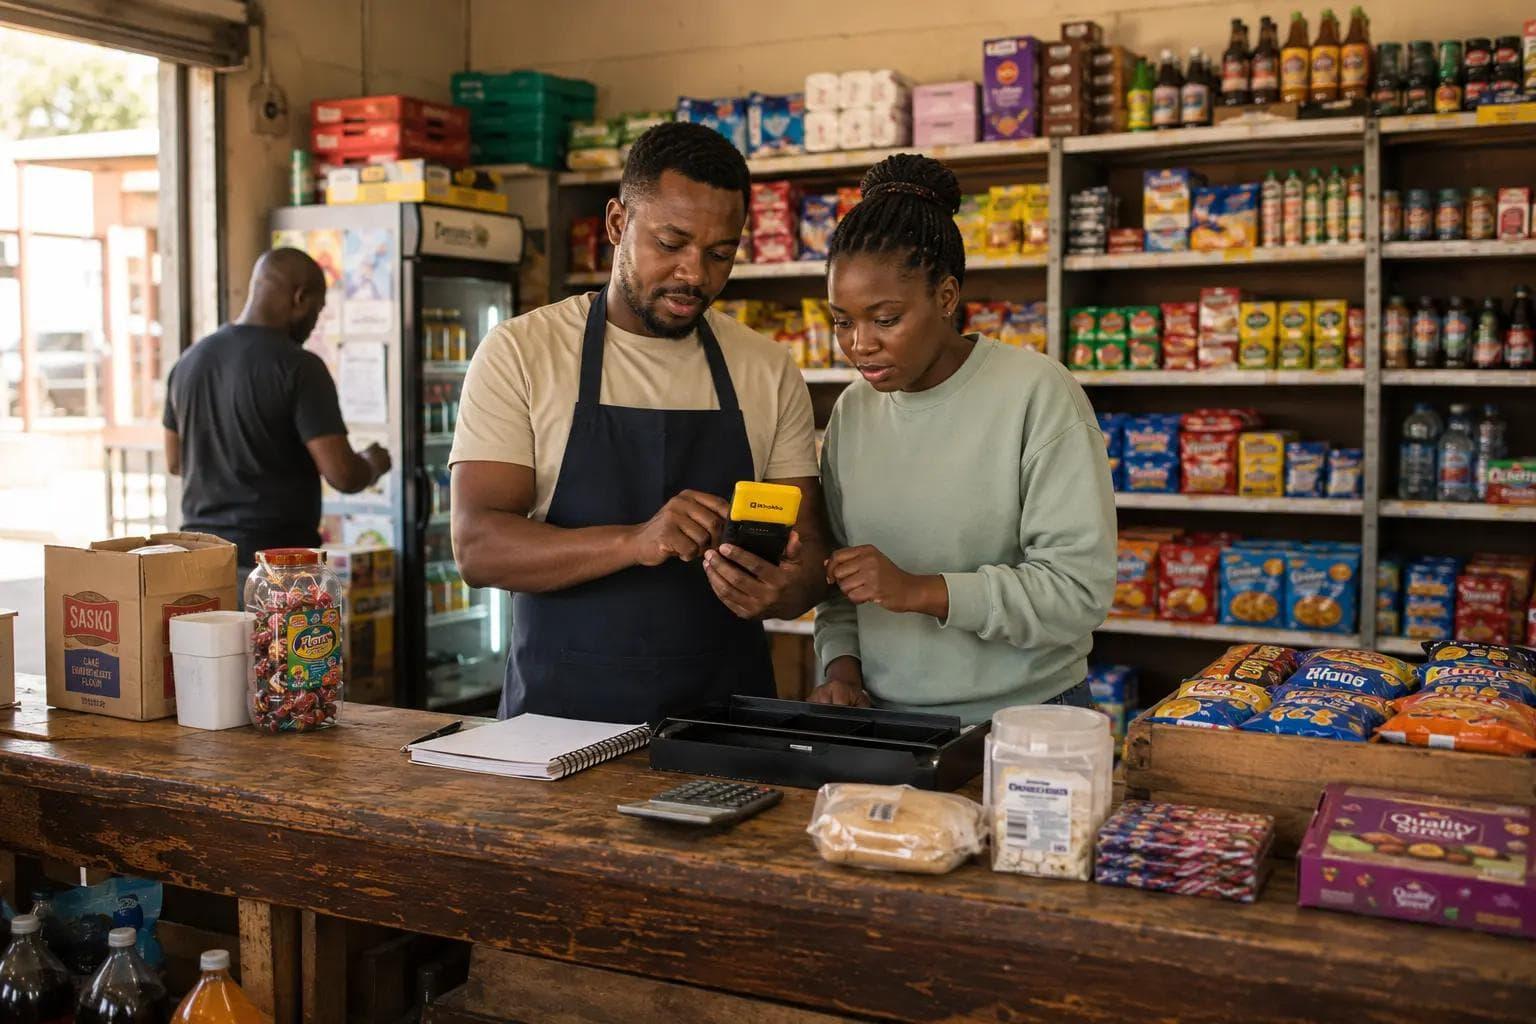
“A study commissioned by British International Investment and Swedfund identifies a reported US$45 billion funding gap facing black-owned and black-led businesses, with South African firms particularly struggling to progress from small and medium-sized enterprises into larger companies. The findings raise questions about access to capital, the effectiveness of economic empowerment policies, and whether entrepreneurs have the financial support needed to grow, compete and create jobs.”
A significant barrier to business growth
South Africa’s economic transformation debate has gained renewed attention following a study identifying a substantial funding gap affecting black-owned and black-led businesses. Published by Business Day on 14 October 2026, the report highlights an important microeconomic problem: entrepreneurs may have viable business ideas, products and customers but still struggle to obtain the capital required to expand their operations.
The study, commissioned by British International Investment and Swedfund, identifies a reported US$45 billion funding gap. It also finds that black-owned and black-led businesses are concentrated in the small-business segment and frequently struggle to develop into larger, established companies. The report says this challenge is particularly pronounced in South Africa compared with Nigeria, Kenya, Ivory Coast and Senegal.
From a microeconomic perspective, the findings concern the relationship between access to finance, business productivity, investment decisions and market competition. When enterprises cannot obtain suitable funding, they may be unable to purchase machinery, employ additional workers, enter new markets or increase production, even when customers are willing to buy their products.
Consequently, a shortage of finance can limit individual firms while also weakening competition across the wider economy.
Understanding the economics of the funding gap
Capital is one of the essential inputs required to operate and expand a business. Entrepreneurs need money to acquire equipment, pay suppliers, rent premises, finance inventory and cover wages before sales revenue becomes available.
For established companies, these expenses can be financed through retained profits, bank loans, investors or other credit facilities. However, smaller enterprises often have fewer financing options because they possess limited collateral, short trading histories or unpredictable cash flows.
Lenders generally evaluate the probability that a borrower will repay a loan. Businesses with insufficient financial records or limited assets may therefore face stricter requirements, higher borrowing costs or rejected applications.
These decisions can be commercially understandable from an individual lender’s perspective. Nevertheless, they may prevent productive businesses from accessing the resources needed to become more profitable.
This creates a market problem in which promising enterprises cannot grow because they lack funding, while their limited scale makes them appear less attractive to lenders.
The result can be a cycle of restricted investment, slow productivity growth and limited employment creation. Breaking that cycle requires funding mechanisms that assess genuine business potential while maintaining responsible lending standards.
The challenge of moving beyond small-business status
The study highlights the difficulty many black-owned enterprises face in progressing from small and medium-sized businesses into larger companies.
Business expansion usually requires more than an initial investment. A growing enterprise must finance additional stock, recruit employees, improve management systems, acquire technology and establish dependable distribution channels.
For example, a small manufacturer that receives a major supply contract may need to purchase raw materials and pay workers weeks before the customer settles the invoice. Without working capital, the business might be unable to accept the contract, even if fulfilling it would generate a profit.
Similarly, a retailer may identify demand in another town but lack the resources to lease premises, transport merchandise and maintain sufficient inventory.
These examples illustrate why access to finance influences business decisions at every stage of development. Funding shortages can prevent firms from taking advantage of opportunities, restricting their ability to compete with larger companies that already possess established credit relationships.
However, finance is not the only requirement for sustainable expansion. Entrepreneurs also need reliable customers, skilled workers, sound financial management, appropriate infrastructure and access to markets.
Effective business-development strategies must therefore combine capital with practical support.
Historical inequality and access to capital
The report connects the funding problem to historical and structural factors, including apartheid’s enduring influence on business ownership and access to capital. It also notes concerns about unintended consequences associated with broad-based black economic empowerment, commonly known as B-BBEE.
South Africa introduced economic redress measures to address longstanding inequalities and broaden participation in economic activity. Nevertheless, the existence of policies intended to improve participation does not automatically guarantee that individual entrepreneurs can secure loans, attract investors or finance expansion.
A company may qualify for opportunities linked to empowerment objectives but still lack the cash required to fulfil a contract. Likewise, a business may have strong demand but insufficient collateral to obtain a conventional commercial loan.
The report also highlights that some black founders who are not South African citizens may be unable to benefit from B-BBEE frameworks, even when their businesses are black-owned and led. It further identifies perceptions that some South African black-owned companies owe their success primarily to policy support rather than commercial competitiveness.
These findings underline the importance of distinguishing between ownership, access to opportunities and the financial capacity to operate successfully.
Economic transformation ultimately depends on whether enterprises can develop sustainable products, win customers, generate profits and remain competitive over time.
How restricted finance affects competition
Access to capital influences the structure of markets because firms with sufficient funding can often operate at a larger scale.
Larger businesses may negotiate lower prices from suppliers, invest in efficient equipment and distribute products across wider geographical areas. These advantages can reduce their average costs and strengthen their competitive position.
Smaller competitors without comparable financing may struggle to match prices, maintain stock or invest in marketing. Even when their products are competitive, financing constraints can prevent them from reaching enough customers.
Over time, these differences can affect consumer choice. If smaller firms cannot enter markets or expand, customers may have fewer alternatives, while established businesses face less pressure from emerging competitors.
Access to appropriate finance can help new firms enter markets and established small businesses improve their productivity. Greater competition may encourage businesses to innovate, improve customer service and offer more attractive prices.
However, simply increasing the volume of lending is not sufficient. Finance must reach businesses with viable plans, and repayment conditions must reflect their cash flows and commercial risks.
Poorly designed loans can increase debt burdens without improving productivity. Responsible financing should therefore consider both the entrepreneur’s growth potential and the business’s ability to repay.
The proposed transformation fund
The Business Day report quotes Black Business Council chief executive Kganki Matabane, who argues that B-BBEE remains relevant but needs to be complemented by a transformation fund capable of supporting black-owned businesses. He argues that legislation was not matched by a dedicated financing mechanism operating at the required scale.
A transformation fund could potentially address gaps between conventional commercial lending and the financing requirements of enterprises seeking to expand.
Depending on its design, it might provide loans, equity investments, guarantees or blended finance combining public and private capital. Different instruments suit different businesses: loans may support predictable cash flows, while equity investment may be more appropriate for high-growth companies that cannot safely take on additional debt.
A well-designed fund would need transparent eligibility requirements, independent assessment, measurable outcomes and effective oversight. It should also avoid directing resources solely towards politically connected applicants or businesses that lack viable commercial plans.
Importantly, financing programmes should assess whether recipients create sustainable economic value. Relevant indicators include business survival, productivity, revenue growth, employment, repayment performance and the ability to attract additional private investment.
The fund’s success would ultimately depend on whether it enables businesses to become more productive and financially sustainable rather than simply increasing the number of funding applications approved.
Alternative approaches to business financing
A transformation fund is one possible response, but other measures could also improve access to capital.
Credit guarantees, for example, can encourage financial institutions to lend to viable businesses that lack sufficient collateral. Under an appropriately structured guarantee, a public institution or another guarantor shares part of the lender’s potential losses.
This can reduce the risk associated with financing smaller enterprises, although guarantees must be carefully managed to limit public financial exposure.
Invoice financing is another option. Businesses with confirmed invoices from reliable customers may use those receivables to obtain working capital before the invoices are paid. This can be particularly useful for suppliers that need to pay employees and purchase materials while waiting for payment.
Equity investment can support businesses with substantial growth potential, while development-finance institutions may provide longer-term funding for projects that conventional lenders consider too risky.
Business support is equally important. Training in bookkeeping, financial planning, governance and contract management can help entrepreneurs demonstrate their creditworthiness and manage funds effectively.
Government departments and large private companies can also strengthen smaller suppliers by providing clear procurement opportunities and paying invoices on time.
These interventions address different obstacles and should be evaluated according to their costs, accessibility and economic results.
Implications for employment and household incomes
Small businesses are important participants in local economies because they purchase supplies, pay workers and provide goods and services to nearby communities.
When a business expands, it may hire additional employees, increase purchases from local suppliers and serve more customers. These activities can support household incomes and generate further demand for other businesses.
Conversely, when funding constraints prevent expansion, potential employment opportunities may not materialise.
A business unable to finance new equipment may produce fewer goods than demand would justify. An enterprise that cannot secure working capital may turn down profitable contracts. A service provider unable to employ additional staff may be forced to limit the number of customers it serves.
These limitations can reduce the economic benefits generated by entrepreneurial activity.
Nevertheless, funding alone cannot guarantee job creation. Employment outcomes depend on customer demand, productivity, technology, labour costs and the wider business environment.
Policymakers should therefore evaluate financing initiatives against measurable improvements in business performance rather than assuming that every loan automatically produces additional jobs.
Policy debate and accountability
The funding question is also connected to a wider political disagreement over how South Africa should pursue economic transformation.
The Business Day report notes that the Democratic Alliance has argued for changes to B-BBEE, while Matabane supports retaining the framework and strengthening its financial support. It also discusses a proposal from presidential economic advisory council member Kuben Naidoo for a voluntary tax surcharge linked to BEE compliance certification.
These proposals reflect different views about how to finance economic inclusion and distribute opportunities.
Whatever approach policymakers choose, its effectiveness should be assessed against clear evidence. Important questions include whether capital reaches businesses that previously struggled to obtain it, whether funding costs are reasonable, whether opportunities are distributed transparently and whether supported companies become more competitive.
Regular public reporting would help taxpayers, businesses and investors understand the results.
Conclusion: Turning access to capital into economic opportunity
South Africa’s reported US$45 billion funding gap highlights a serious challenge for entrepreneurs seeking to establish, sustain and expand their businesses.
The central microeconomic issue is that enterprises cannot always translate promising opportunities into productive investment when suitable finance is unavailable. These constraints can limit competition, delay expansion and restrict potential employment creation.
Addressing the problem requires more than legislation or isolated funding announcements. Effective solutions should combine accessible capital, responsible lending, transparent governance, business-development support and reliable market opportunities.
A transformation fund could contribute to that effort if it is carefully designed, professionally managed and evaluated against measurable outcomes. Credit guarantees, invoice financing, equity investment and stronger procurement practices may provide additional support.
Ultimately, successful economic transformation should be reflected in the number of businesses capable of surviving, innovating, employing people and competing without permanent dependence on special assistance.
The latest report therefore raises a question that extends beyond financing policy: can South Africa build a business environment in which capable entrepreneurs have a fair opportunity to turn viable ideas into productive, sustainable enterprises?
The answer will depend on whether policymakers, lenders, investors and established companies can convert the debate about economic inclusion into practical mechanisms that help businesses grow.



