




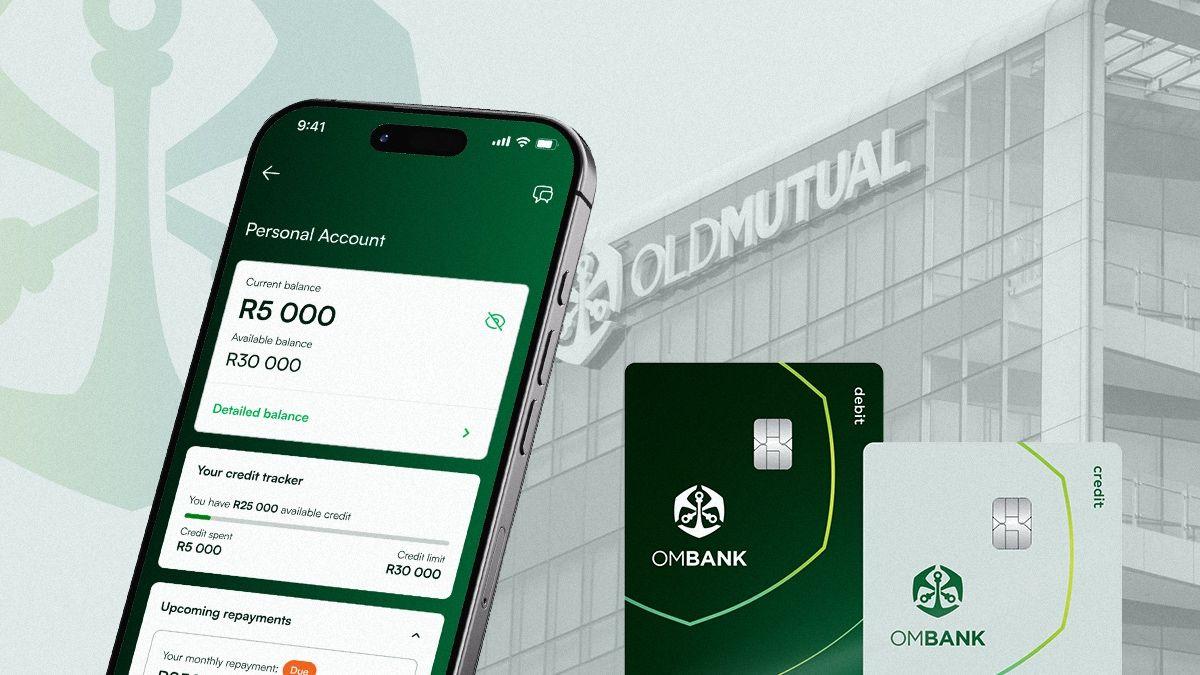
“OM Bank, the banking operation of Old Mutual, is expanding its challenge to South Africa’s established banking sector after reaching about 1 million customers, as it seeks to build a larger presence in the country’s competitive financial-services market. The bank says it intends to focus on customers earning between R15,000 and R50,000 a month, with plans to reach as many as 2.8 million customers by 2028, while Old Mutual continues investing billions of rand in the new banking operation.”
OM Bank Steps Up Competition in South Africa’s Banking Market
South Africa’s banking industry is entering another phase of competition as OM Bank, the banking operation of financial-services group Old Mutual, seeks to expand its customer base and establish itself as a significant participant in the country’s retail banking market.
Moneyweb reported the latest development on 25 September 2026 in an article based on Bloomberg reporting. According to the report, OM Bank reached approximately 1 million customers by September, highlighting how quickly the relatively new bank has built its presence since beginning operations in August 2025.
The expansion is taking place in a banking market where established institutions already have substantial customer bases and large asset positions. Moneyweb reported that 81% of South Africans already have a bank account, meaning that OM Bank is competing not simply to bring previously unbanked consumers into formal banking, but also to persuade existing customers to move some or all of their financial relationships to a different provider.
Old Mutual’s move into banking
OM Bank forms part of Old Mutual’s broader strategy to combine different areas of financial services. Old Mutual has historically operated across insurance, savings and investment services, while South Africa’s banks have increasingly expanded into insurance and other financial products.
According to OM Bank CEO Clarence Nethengwe, the convergence between banking and insurance was a major factor behind Old Mutual’s decision to establish a banking operation. In the interview reported by Bloomberg, Nethengwe said banks were increasingly moving into insurance, prompting Old Mutual to enter banking from a competitiveness perspective.
The development illustrates a wider change in financial services. Traditional boundaries between banks, insurers, investment businesses and technology companies have become less distinct as financial institutions seek to provide customers with multiple products through integrated digital platforms.
Old Mutual’s own reporting describes OM Bank as a digital-first operation designed around banking services and says its rollout has been deliberately phased, with monthly break-even targeted during 2028.
OM Bank is also formally recognised within South Africa’s banking regulatory framework. The South African Reserve Bank’s list of locally controlled banks includes OM Bank Limited and identifies Tsakani Clarence Nethengwe as its chief executive officer.
One million customers
One of the most significant figures in the latest report is OM Bank’s customer growth.
Moneyweb reported that the bank attracted nearly 4,500 customers per day during the eight months to August and reached approximately 1 million customers by September. About 68% of those customers were already Old Mutual customers, while the remaining 32% were new to the wider Old Mutual group.
This customer composition is important because Old Mutual has an established base of customers across its insurance, savings and financial-services businesses.
Existing customers provide the company with a potential distribution channel for banking products. Instead of acquiring every banking customer from the wider market, OM Bank can introduce banking services to people who already have a relationship with Old Mutual.
At the same time, the 32% share of customers who are new to the Old Mutual group indicates that the bank is also attempting to attract consumers who did not previously use Old Mutual’s other financial products.
Focus on the middle market
OM Bank’s strategy is centred on a specific section of the South African consumer market.
According to the latest Moneyweb report, the bank is targeting customers earning approximately R15,000 to R50,000 per month. It aims to increase its customer base to as many as 2.8 million people by 2028.
This strategy places OM Bank in direct competition for customers who are already attractive to established retail banks and newer digital banking businesses.
South Africa’s consumers have increasingly been offered banking products through mobile applications, digital account opening, electronic payments, rewards programmes and other technology-based services. Consequently, a new bank needs to differentiate itself not only through physical branches but also through its digital experience, pricing, products and relationship with customers.
OM Bank’s digital-first model reflects this changing environment.
The bank’s own materials describe the operation as focusing on security, reliability, scalability and a digital customer experience.
Billions invested in the new bank
Building a new banking operation requires significant investment in technology, regulatory infrastructure, cybersecurity, personnel and customer acquisition.
Moneyweb reported that Old Mutual initially spent approximately R2 billion establishing OM Bank and subsequently injected a further R3.2 billion between 2025 and 2026. The company has budgeted another R2 billion through 2028, when the bank is expected to reach break-even or profitability.
These figures demonstrate that Old Mutual is treating banking as a long-term strategic investment rather than simply an additional product line.
The timing of profitability is also significant. A new bank can accumulate customers rapidly while still recording substantial investment costs. Reaching break-even therefore depends not only on customer numbers but also on the value of customer relationships, deposits, lending, transaction activity and operating efficiency.
Old Mutual’s 2025 integrated report similarly stated that OM Bank’s rollout was phased and that the group was targeting monthly break-even during 2028.
Deposits and the Old Mutual ecosystem
OM Bank also plans to use Old Mutual’s existing savings and insurance ecosystem to support growth.
The latest report says the bank intends to leverage an existing insurance-savings product with approximately R32 billion accumulated over time. That pool was reported to grow by about R1.5 billion annually, and OM Bank aims to use the opportunity to build deposits of as much as R10 billion by 2028.
Deposits are an important part of banking because they provide funding for banking activities and strengthen the relationship between customers and the institution.
For OM Bank, therefore, the Old Mutual customer base potentially provides two advantages: an existing audience for banking products and an established pool of savings relationships.
However, converting insurance or savings customers into active banking customers is different from simply registering customers on a banking platform. Sustained banking relationships generally depend on regular transactions, deposits, payments, borrowing and other financial activity.
Competition with established banks
The competitive environment remains significant.
Moneyweb reported that Standard Bank Group, FirstRand, Absa Group and Nedbank Group together held about 83% of South Africa’s R5.8 trillion in banking assets, according to the figures cited in the Bloomberg report.
That concentration means OM Bank is entering a market dominated by large institutions with substantial financial resources, established brands and extensive customer relationships.
At the same time, South Africa’s banking landscape includes a growing number of digital and specialist competitors.
Discovery Bank has already established a banking operation, while Sanlam has received approval to provide transactional banking services through a partnership with GoTymebank, with a planned launch in the first quarter of 2027, according to the latest Moneyweb report.
This means competition is developing not only between traditional banks but also between financial-services groups that are expanding into banking.
Technology and changing customer expectations
Digital banking is an important part of this competitive environment.
Customers can increasingly open accounts, transfer money, make payments, monitor savings and access financial information through mobile applications. This reduces the importance of traditional branch networks for some banking activities.
OM Bank has positioned itself around a digital-first model, while other South African banks are also investing heavily in technology, artificial intelligence, digital payments and mobile banking.
The broader banking industry is therefore competing on several fronts simultaneously: price, convenience, technology, rewards, lending, savings, security and the ability to provide customers with multiple financial products.
For consumers, the growth of new banking providers creates more opportunities to compare products and services. For banks, it increases the pressure to retain customers and demonstrate value.
What the expansion means for South Africa’s banking sector
OM Bank’s expansion is significant because it adds another major financial-services group to an already competitive banking market.
Its growth to approximately one million customers indicates that a new banking operation can build scale relatively quickly when supported by an established financial-services group.
However, customer numbers alone do not determine the long-term performance of a bank. OM Bank still has to convert its growing customer base into sustainable deposits, transactions, lending activity and revenue while controlling operating and technology costs.
The bank’s stated break-even target of 2028 provides an important benchmark for measuring that progress. Old Mutual has committed substantial capital to the operation, while its strategy relies on continued customer growth and greater integration between banking and its existing financial-services businesses.
The next stage will therefore be closely connected to how effectively OM Bank turns its expanding customer base into an established banking franchise.
Outlook
South Africa’s banking sector is undergoing continued structural change as established banks expand into insurance, insurers enter banking and fintech businesses introduce new digital financial products.
OM Bank’s latest customer milestone places it firmly within that changing landscape. Its strategy combines Old Mutual’s existing customer relationships with a digital banking platform and a targeted middle-market customer segment.
The bank’s plans to reach up to 2.8 million customers by 2028, build deposits and achieve break-even demonstrate the scale of its ambitions.
For the South African banking industry, the development adds another competitor seeking to capture customers and financial activity from an already concentrated market. For consumers, the expanding number of banking providers means that account fees, interest rates, digital services, security, lending terms and customer support remain important factors when evaluating banking products.
The significance of OM Bank’s expansion will ultimately become clearer as it moves from rapid customer acquisition toward the more demanding stage of building a sustainable and profitable banking business.



